Second-Home Loan Cap Raised From 60% to 70%, but More Viewings Have Not Clearly Translated Into More Deals
After the central bank eased the loan-to-value cap on second-home mortgages for individuals, agents in many areas report more inquiries, but a gap remains between owners' asking prices and buyers' expectations.

- Anue reported that the central bank raised the loan-to-value cap on second-home mortgages for individuals from 60% to 70%, with more viewings but no clear pickup in deals.
- CTBC Real Estate General Manager Zhang Shizong said buyers hope for lower prices while sellers do not easily make concessions, and that this gap in price perception is the main reason deals have not picked up.
- For nationwide deal volume in October 2026, CTBC Real Estate was down 0.6% from the previous month, while Sinyi... HouseFun franchise stores were up 9.0% from the previous month.
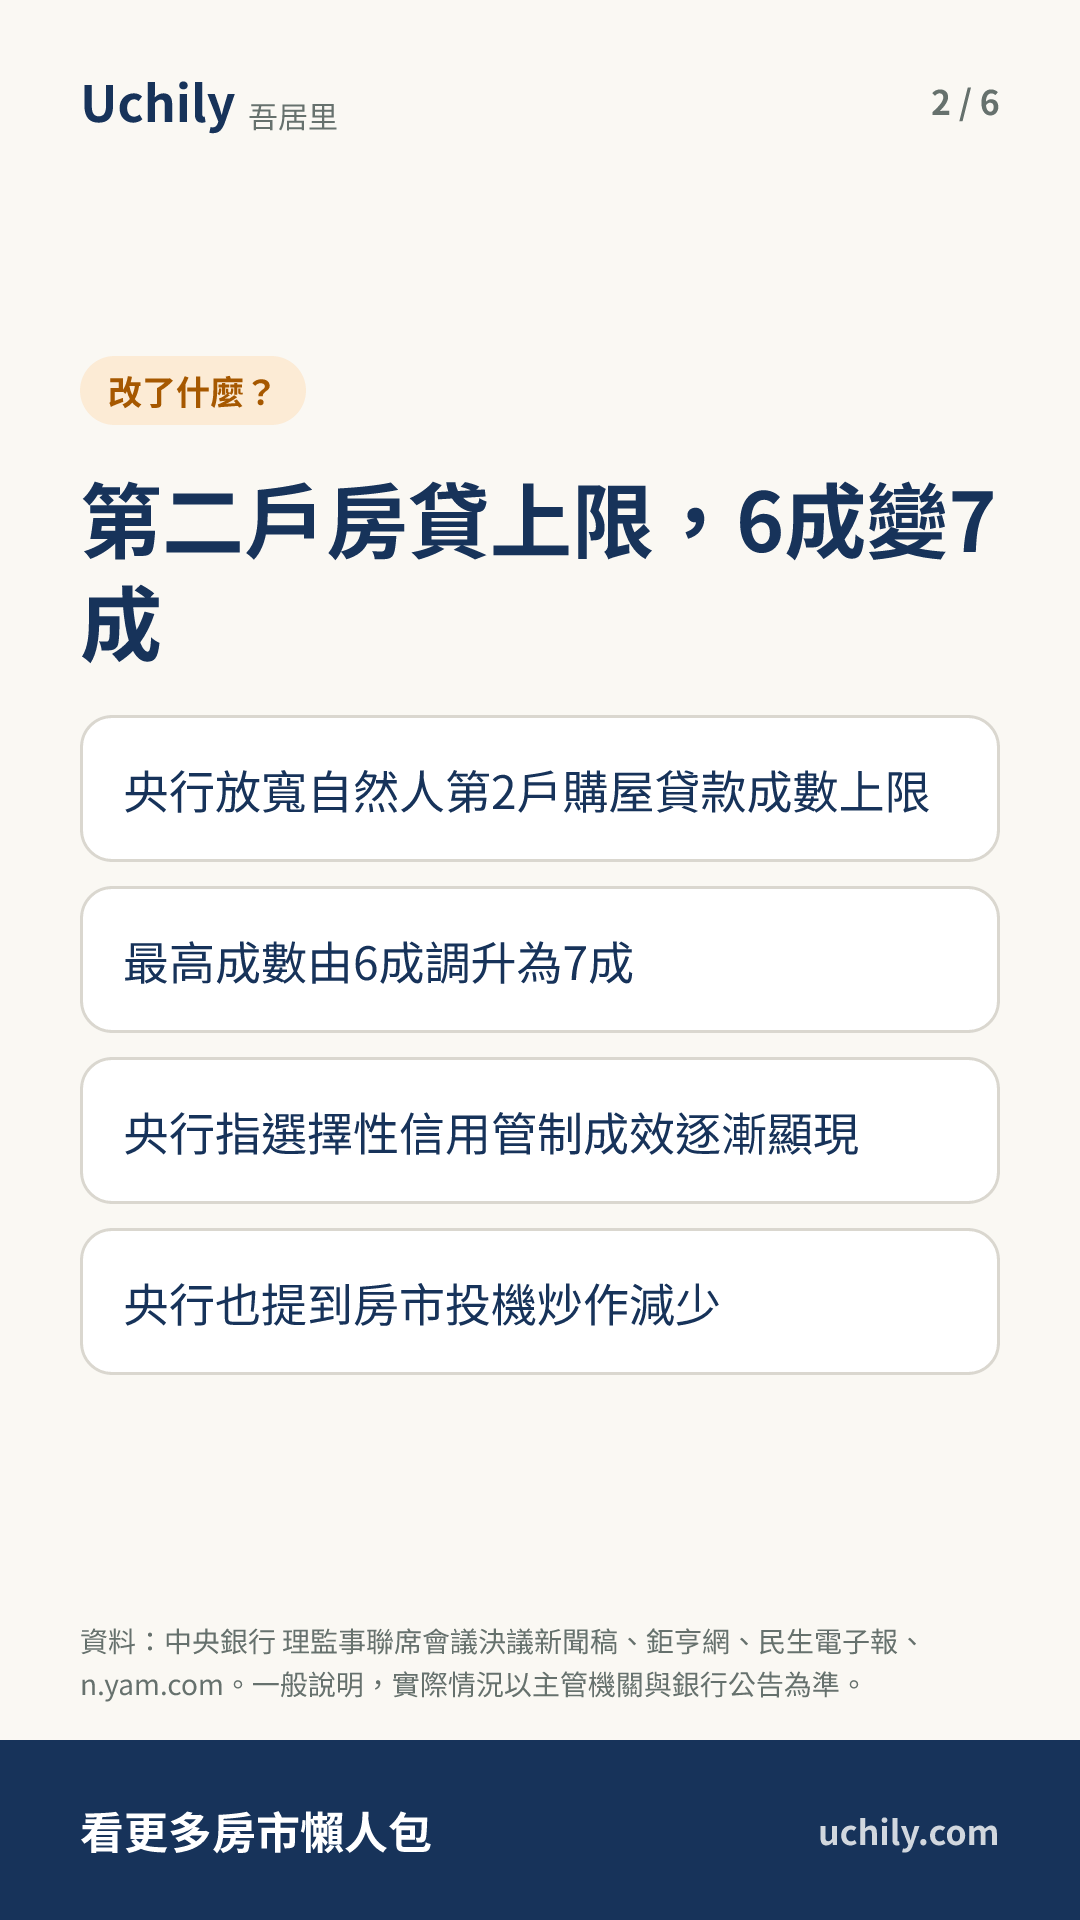
At its board meeting on September 17, the central bank decided to hold interest rates for the 10th consecutive time and, at the same time, eased selective credit controls, raising the loan-to-value cap on second-home mortgages for individuals from 60% to 70%. In its press release on the decision, the central bank explained that after the seventh adjustment of the controls in September 2024, the loan-to-value ratios banks could offer fell, property transactions continued to cool and the pace of price increases slowed. It said this move also responds to public petitions stating that second-home loans for individuals are "for family members or oneself to buy a home for owner-occupation."
After the easing, the market mood changed, but deals have not kept up. Zhang Shizong said that buyers' willingness to view properties has clearly risen since the easing, but the number of cases actually concluded is not yet visible. Xu Jiaxin, executive director of the Planning and Research Office at HouseFun, said the central bank's clear stance helps buying sentiment, especially among those looking to trade up, but prices remain firm and the shadow of areas with selling pressure is still there.
The two agencies' October deal statistics cover different scopes. CTBC Real Estate counts its own internal deals, which were up about 3% nationwide from a year earlier; HouseFun counts deals at its franchise stores, which were up 7.4% nationwide from a year earlier.
Local agents' observations are similar. Yilan agent He Li said that Yilan does not lack demand for home purchases, but buyers are more price-sensitive and are in no hurry to make offers even after viewing. New Taipei agent Dai Yuling said that viewing volume has recovered slightly, while buyers' willingness to make offers and sign contracts remains conservative, and that the overall recovery in buying sentiment is "faster in the north, slower in the south."
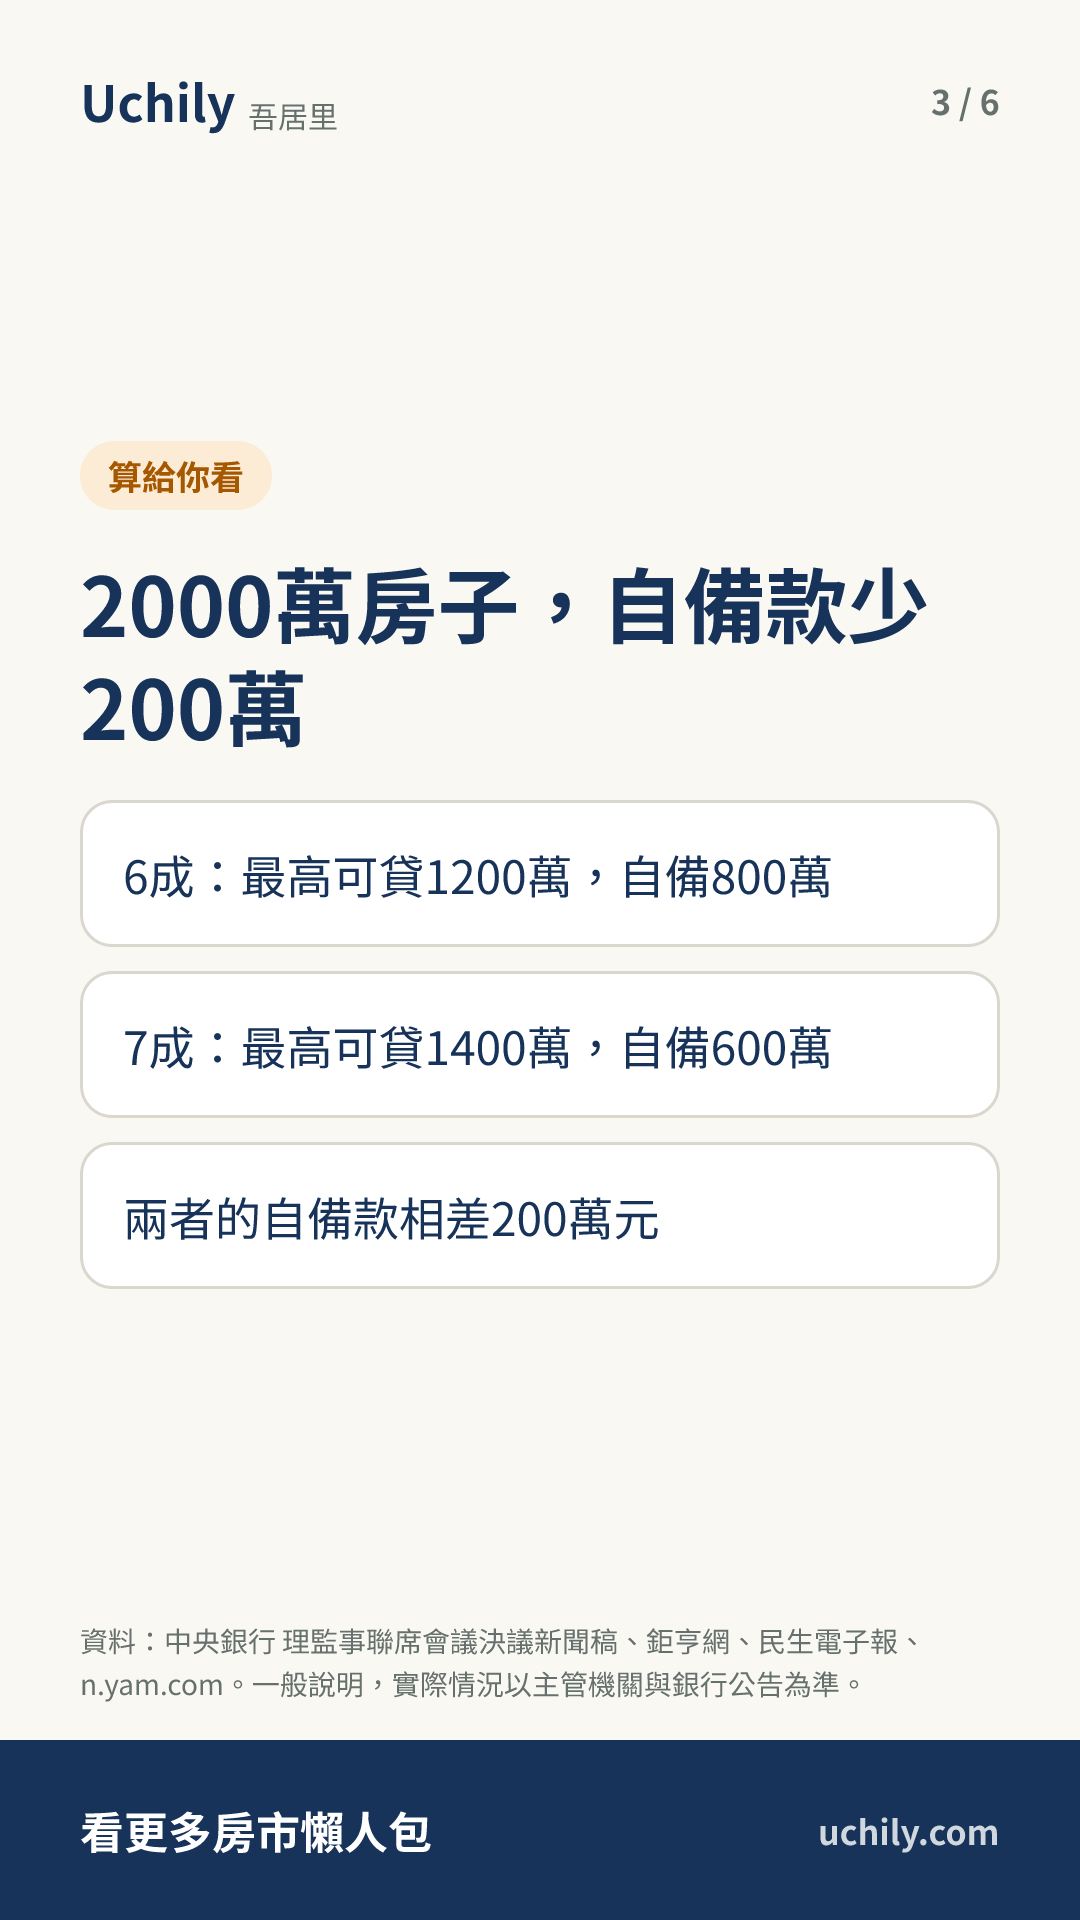
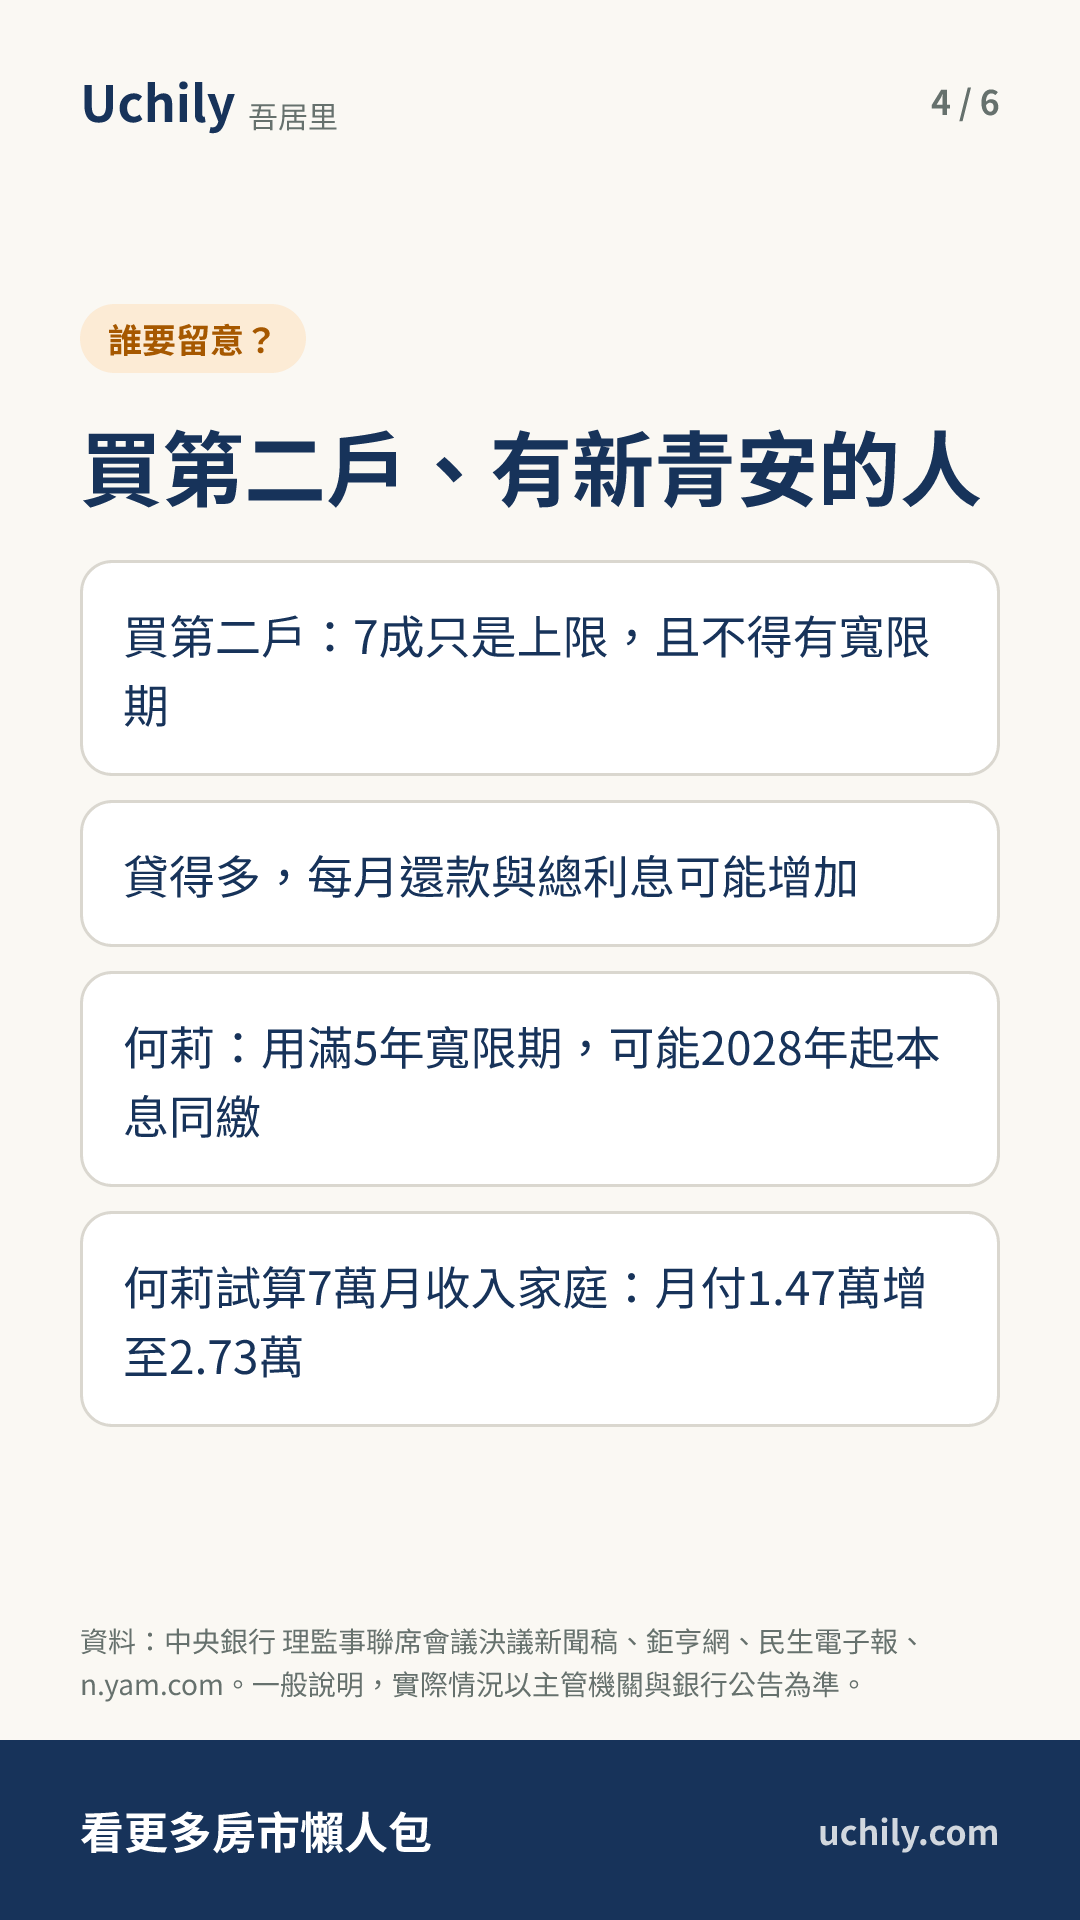
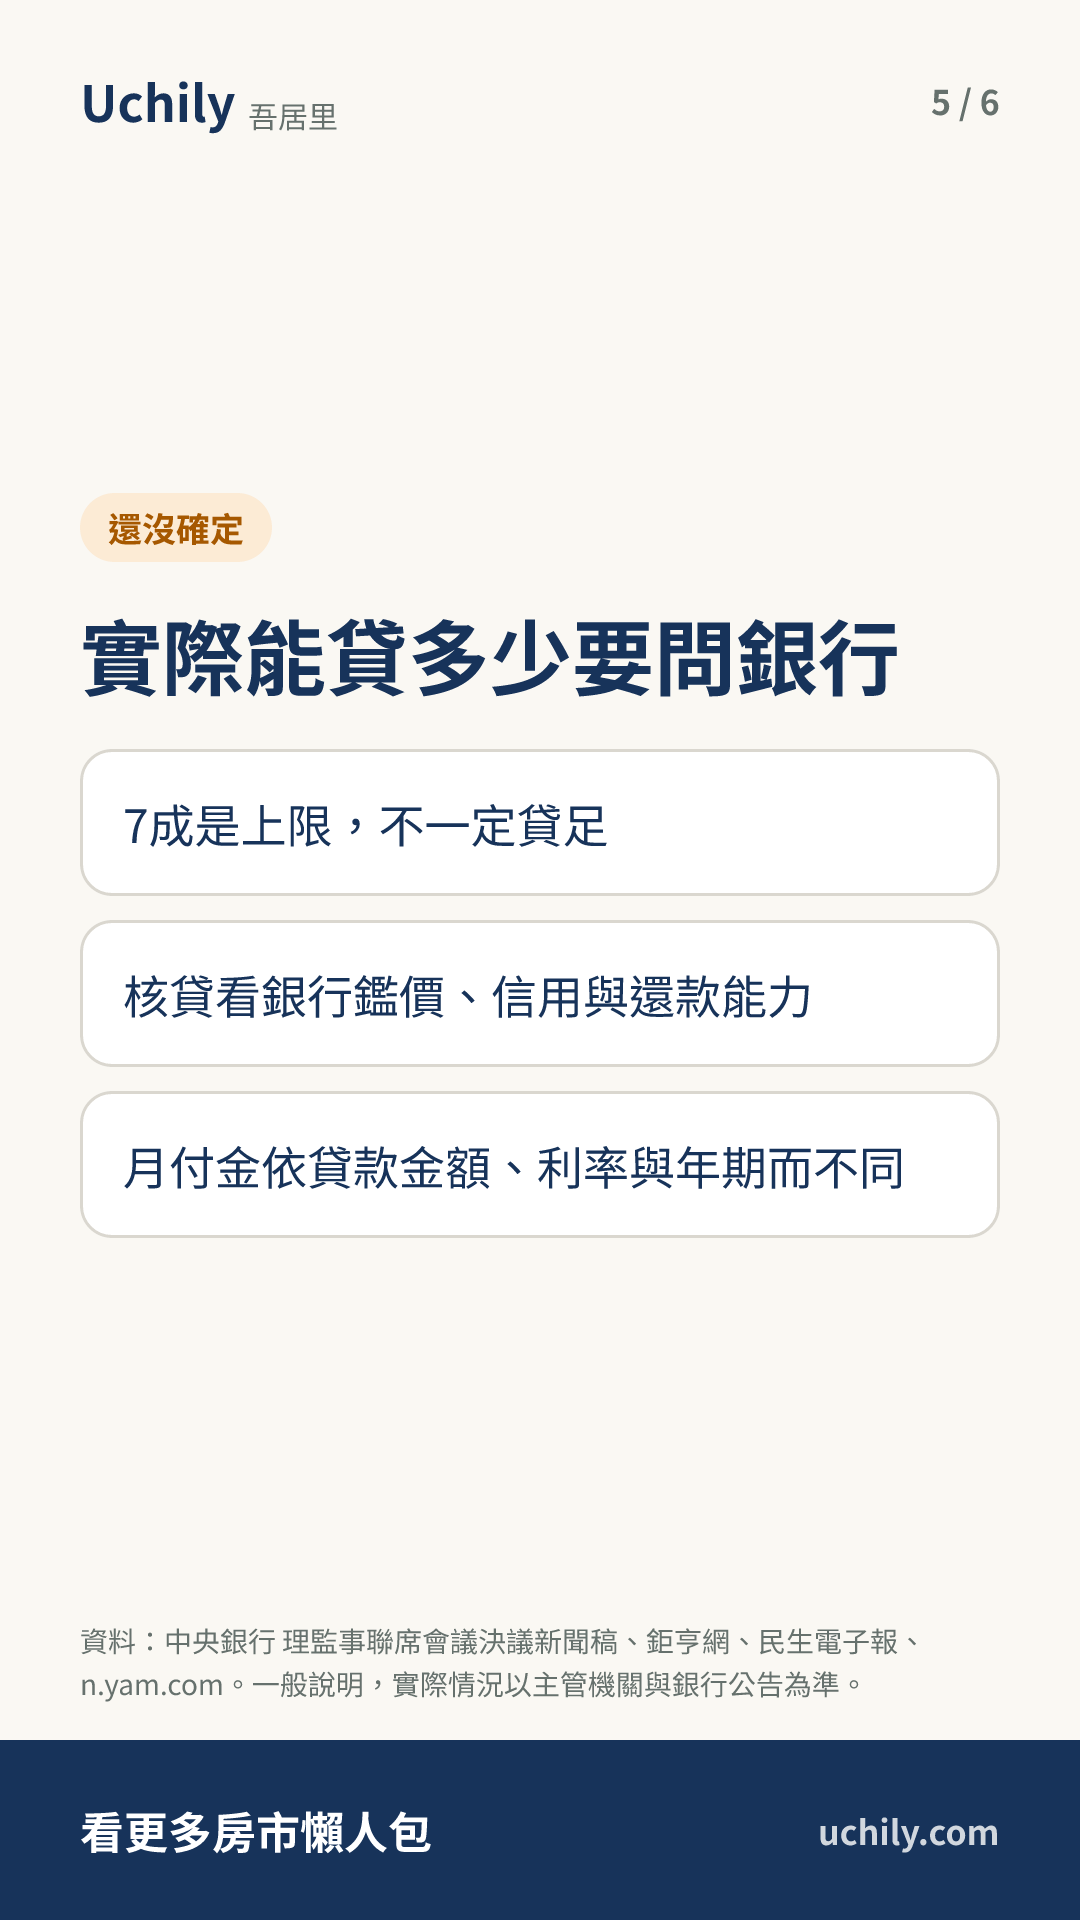
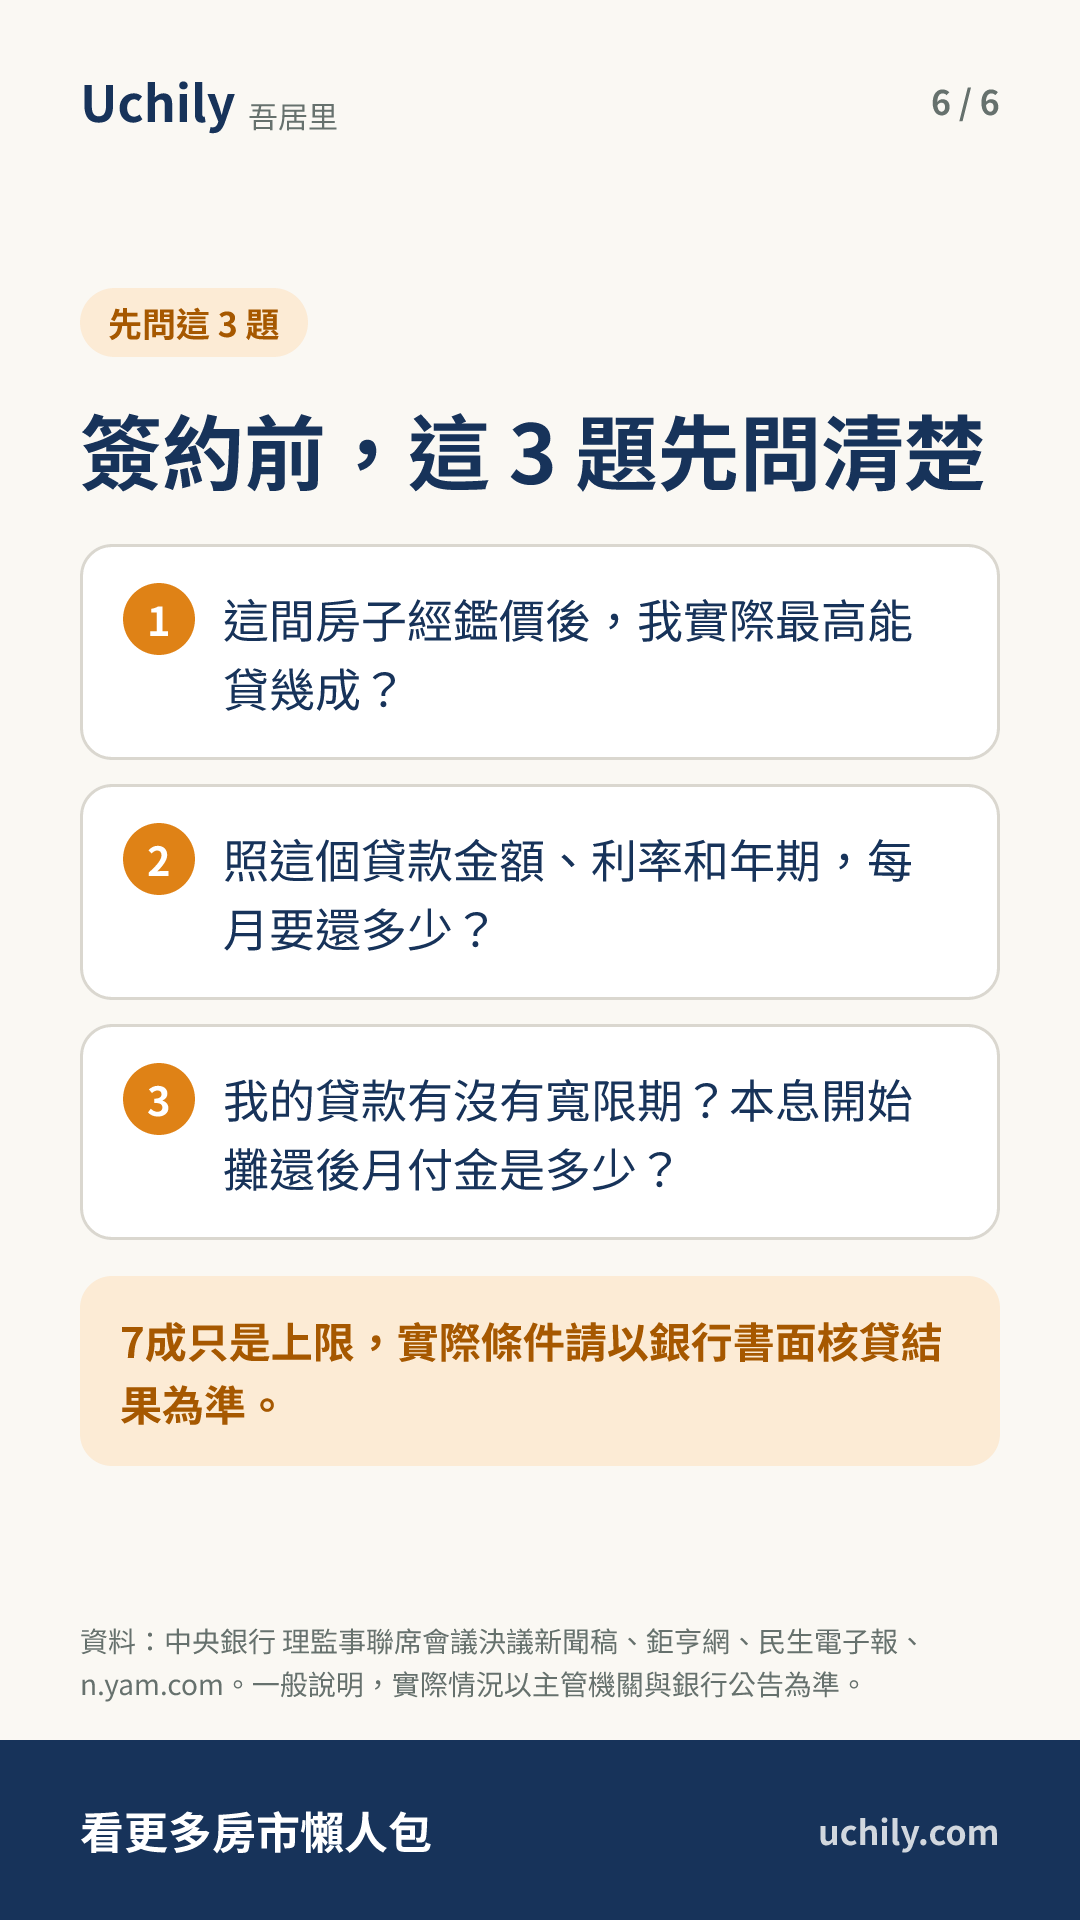
For a home with a total price of NT$20 million, at a 60% loan-to-value ratio the maximum loan is NT$12 million and the down payment is NT$8 million; after the increase to 70%, the maximum loan is NT$14 million and the down payment is NT$6 million, a difference of NT$2 million. Actual loan approval still depends on the bank's valuation, the borrower's credit and repayment ability, so a full 70% is not guaranteed, and after the second-home mortgage ratio rises to 70%, no grace period is still allowed.
For people who want to buy a second home, 70% is only a cap; how much can actually be borrowed is decided by the bank's valuation and review, and there is no grace period, so it may help to confirm the monthly payment with the bank before signing. For those who already have a mortgage, He Li pointed out that for the Youth Home Loan handled starting in 2023, if the full 5-year grace period is used, the first batch of borrowers may begin paying principal and interest together from 2028, and monthly payments will increase.
Loan-to-value calculator
- Loan amount
- 1,400 × NT$10K
- Down payment
- 600 × NT$10K
- Monthly payment
- NT$54,023
- Total interest
- 545 × NT$10K
The default rate of 2.321% is the central bank’s published August average rate on new mortgages at the five major banks. Equal monthly payments, no grace period; the bank’s approval is final.
Quick quiz
2 questions; pick an answer to see the explanation
- For a home with a total price of NT$20 million, what is the maximum loan after the loan-to-value ratio is raised to 70%?
- What does CTBC Real Estate General Manager Zhang Shizong see as the main reason transaction volume has not risen significantly?
Image cards
6 cards. Tap to enlarge; save and share with friends
Original:中央銀行 理監事聯席會議決議新聞稿 · We only post summaries and key points. Read the original for the full story.
This week’s news, sorted for you
One Uchily newsletter a week, picking out what actually affects your wallet.
Subscribing creates a Uchily account with this email; open the link in the email to finish. You can unsubscribe from any email.