Leasing a Rooftop for Solar Panels Still Qualifies for the 2‰ Land Value Tax Rate if Interior Use Is Not Changed
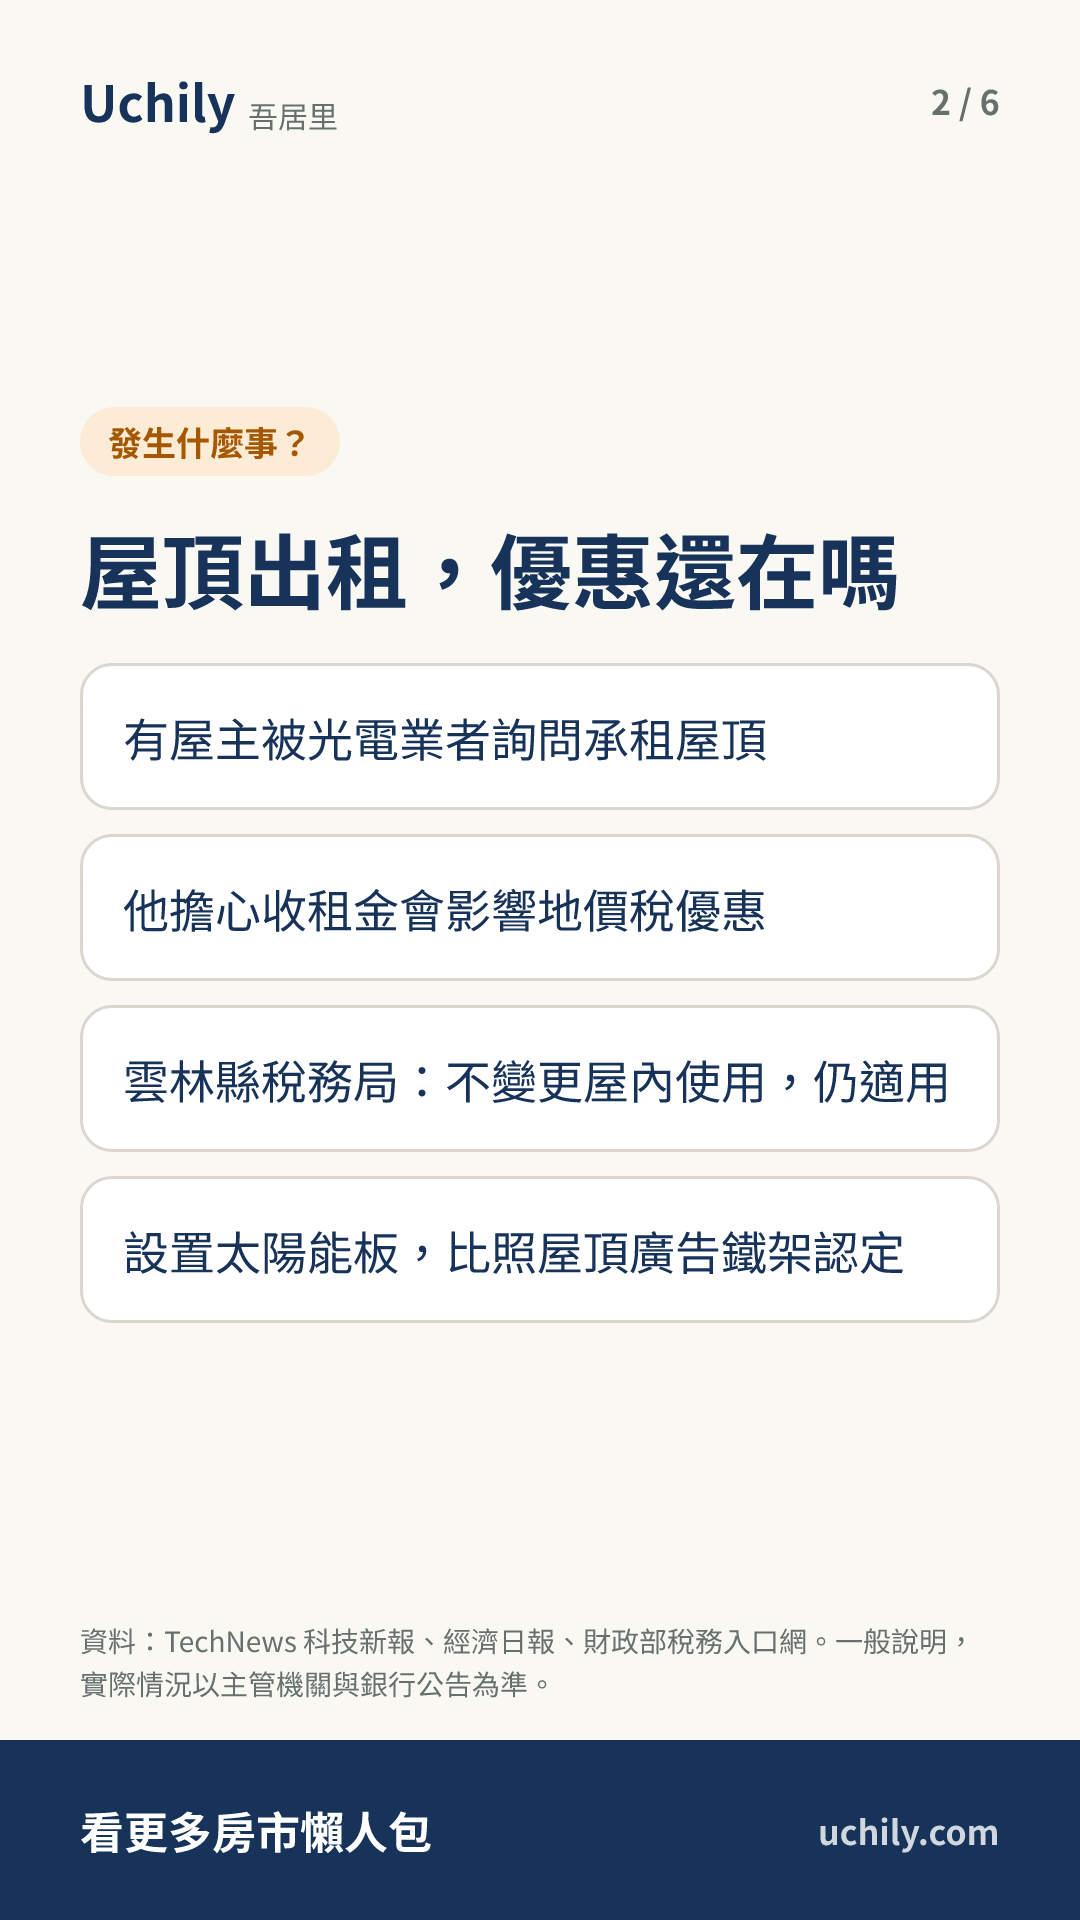
The Yunlin County Tax Bureau explains that when a residential rooftop is leased to a company to install solar panels or a base station, the preferential rate for self-use residential land is not revoked because rent is collected, as long as the interior use of the building is not changed.

- The Yunlin County Tax Bureau says that when a residential rooftop is leased for solar panels, land value tax is still levied at the self-use residential rate as long as the interior use of the building is not changed.
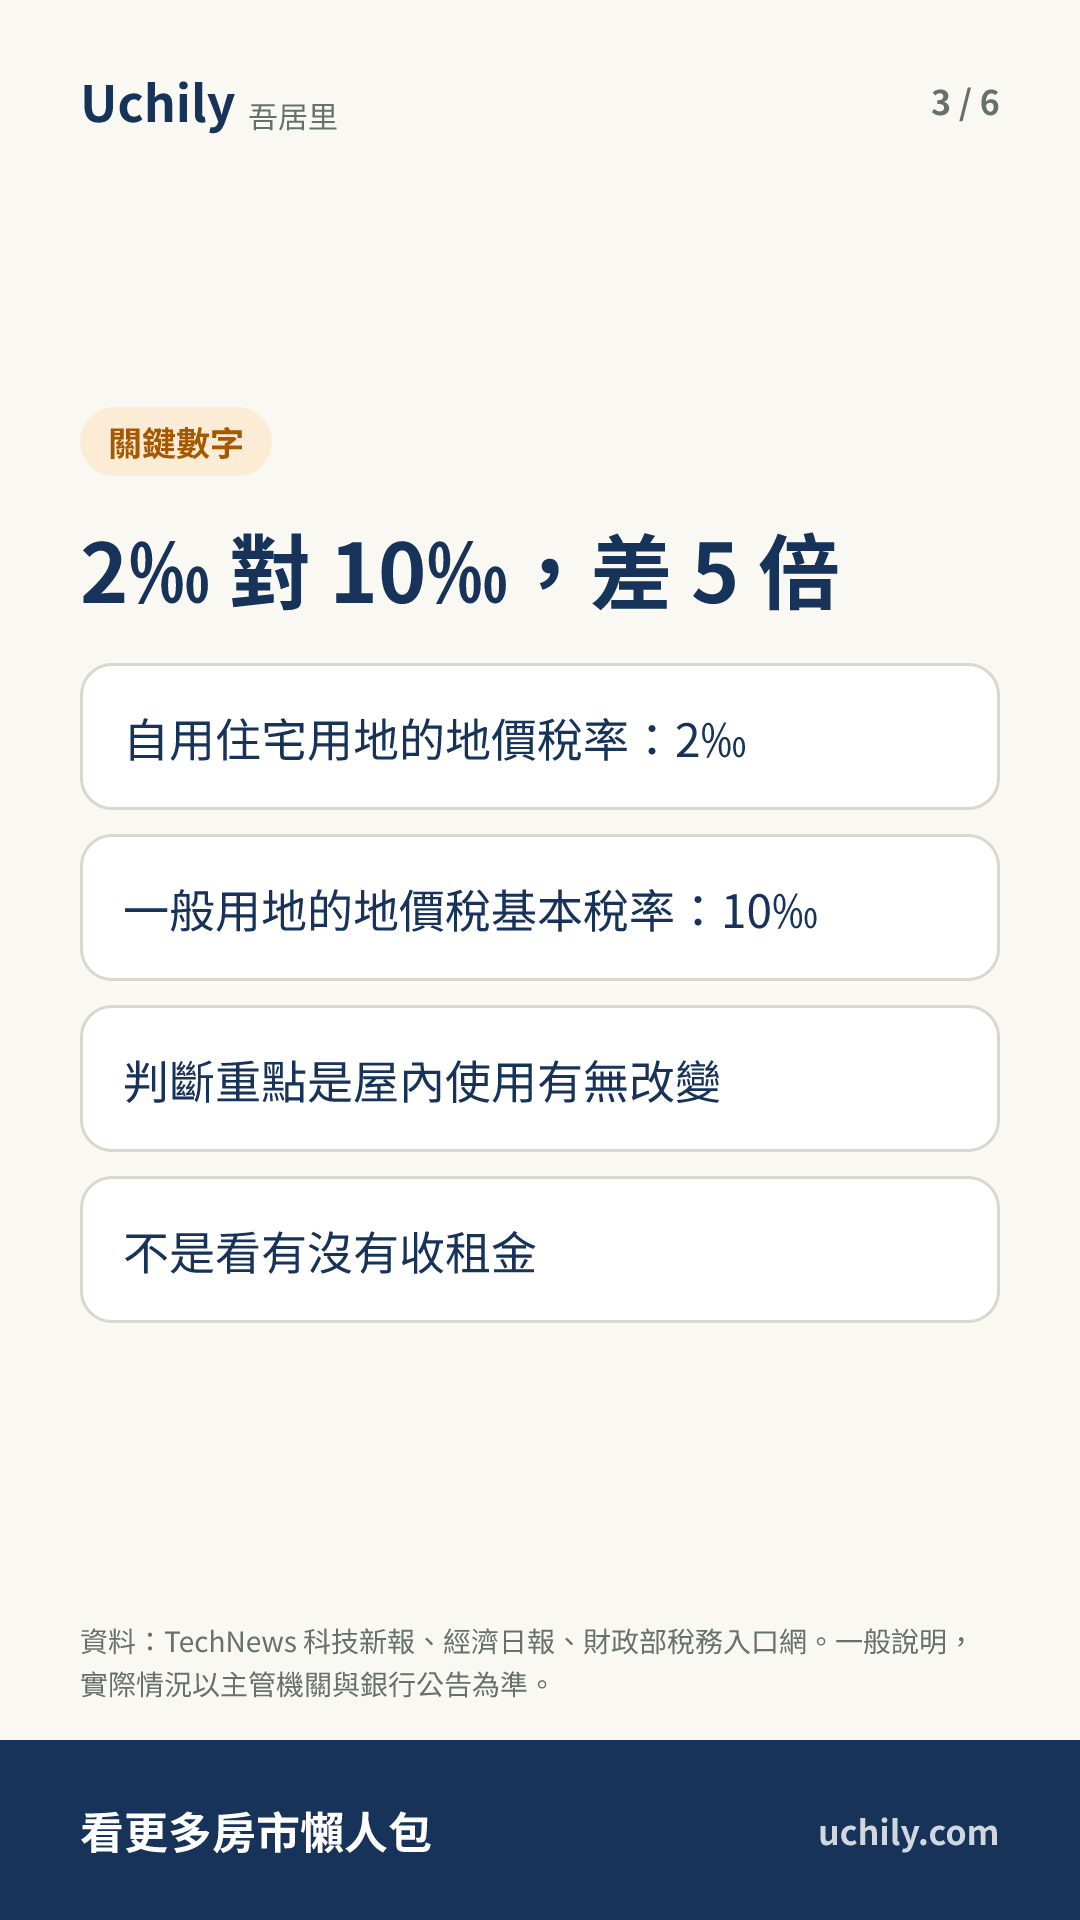
- TechNews (科技新報) reported that the land value tax rate for self-use residential land is 2‰, while the basic rate for general land is 10‰, a difference of 5 times.
- Whether a rooftop leased for solar panels keeps the self-use residential rate depends on whether the original interior use of the building has changed, not on whether rent is collected.
The matter began when a member of the public asked about his recently completed townhouse, whose land had already been approved for land value tax at the self-use residential land rate. A solar power company recently approached him and his neighbors, hoping to lease their rooftops to install solar power generation equipment. He was concerned that collecting rent would affect the land value tax benefit he already had.
The Yunlin County Tax Bureau explained that under Articles 9 and 17 of the Land Tax Act, self-use residential land must meet two conditions: the landowner, or the landowner's spouse or lineal relative, has completed household registration at the site, and the residential land is not leased or used for business. Land that meets these conditions is eligible for the preferential land value tax rate of 2‰.
The Yunlin County Tax Bureau said that under the review principles set by the Ministry of Finance, when a landowner lets others paint advertisements on the exterior walls of a house, hang advertising signboards, or lease the rooftop to put up an advertising iron frame, the residential land can still be regarded as not leased or used for business, even if rent is collected. A residential rooftop leased for a base station or solar panels is treated in the same way as the rule for a rooftop advertising iron frame.
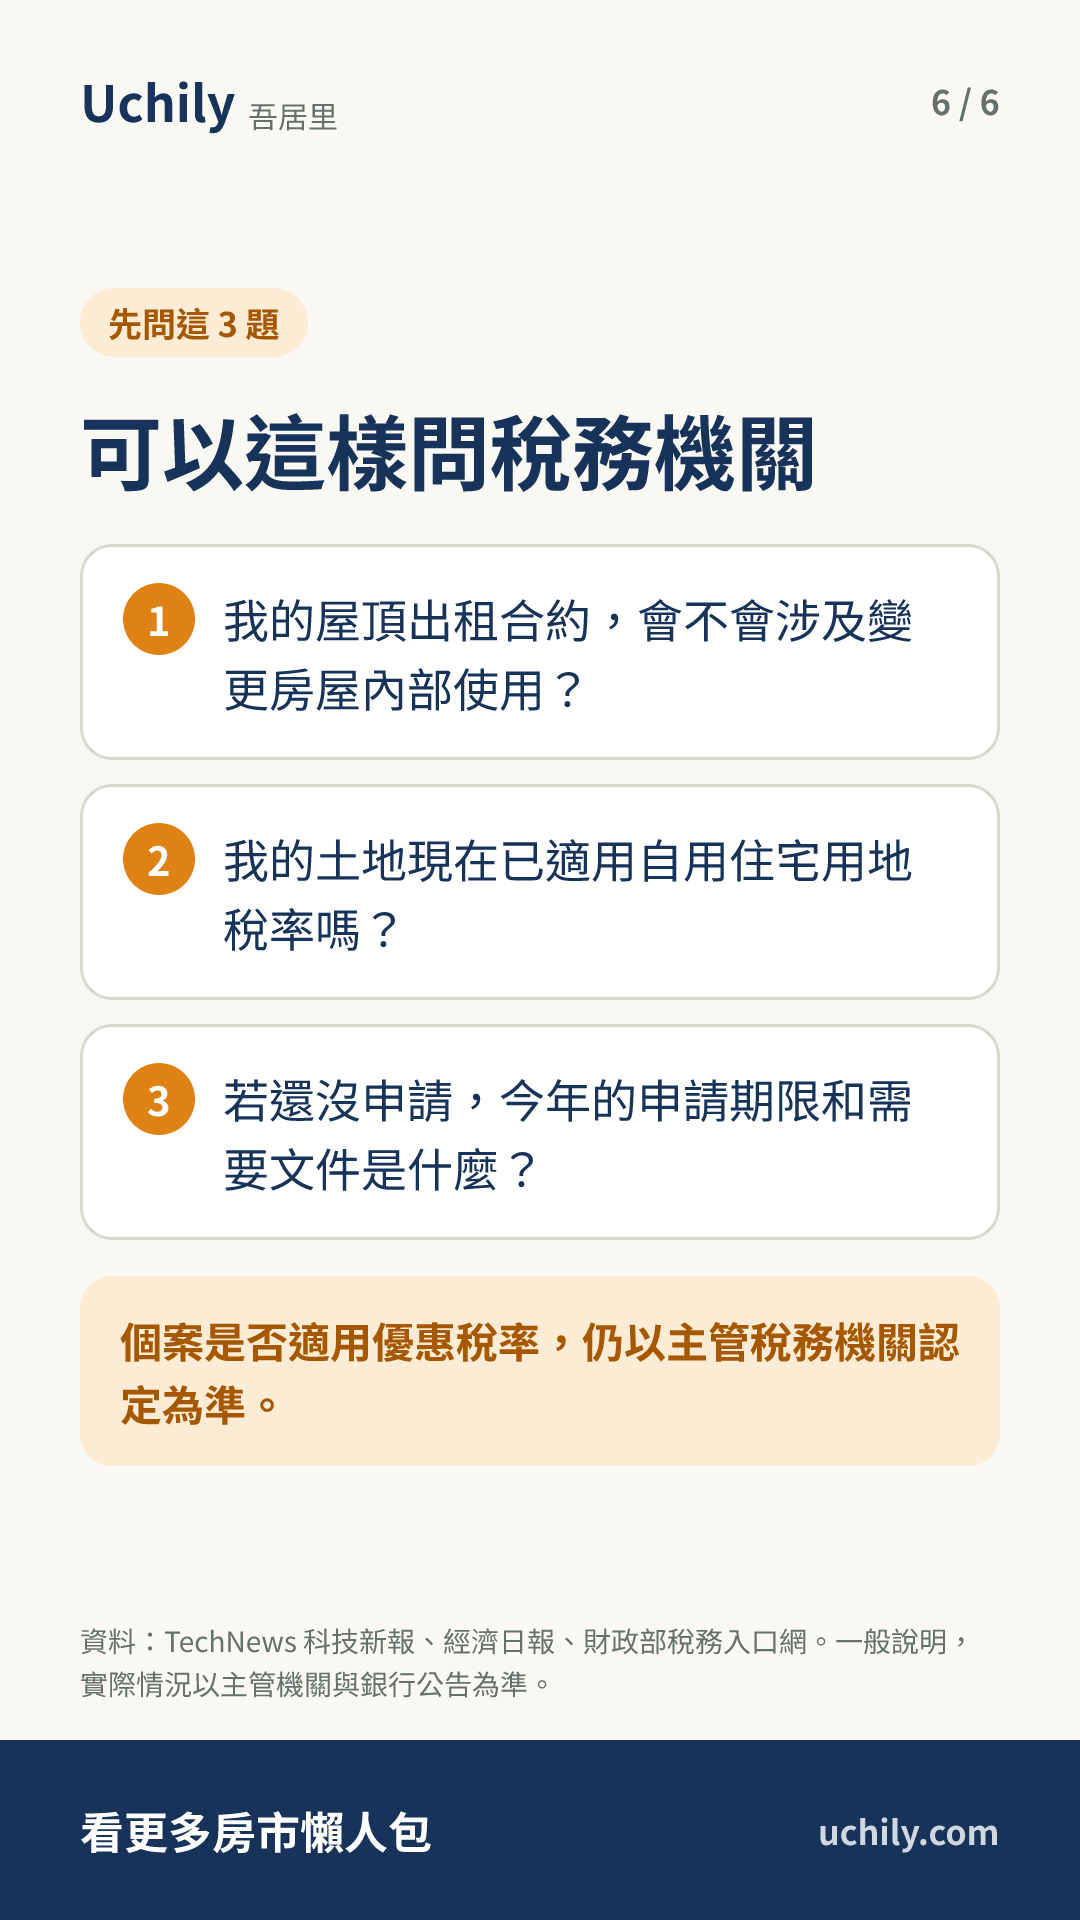
A homeowner leasing the rooftop of a townhouse to a solar power company does not mean the whole building is deemed to be in leased use. The Yunlin County Tax Bureau reminded people who plan to lease a residential rooftop for solar equipment to pay attention to the actual use of the house and the rules on self-use residential land, and said that whether an individual case meets the conditions for the preferential tax rate must still be determined according to the actual circumstances.
The Datun Branch of the Taichung City Government Local Tax Bureau said that when only part of a building on the land is leased or used for business, land value tax can still be assessed at the self-use residential land rate based on the share of the land area corresponding to the part actually used as a residence. The branch also explained that applications must be submitted at least 40 days before land value tax collection begins each year (that is, by September 22 each year) to apply for that year; applications submitted after the deadline take effect starting with the period after the year of application.
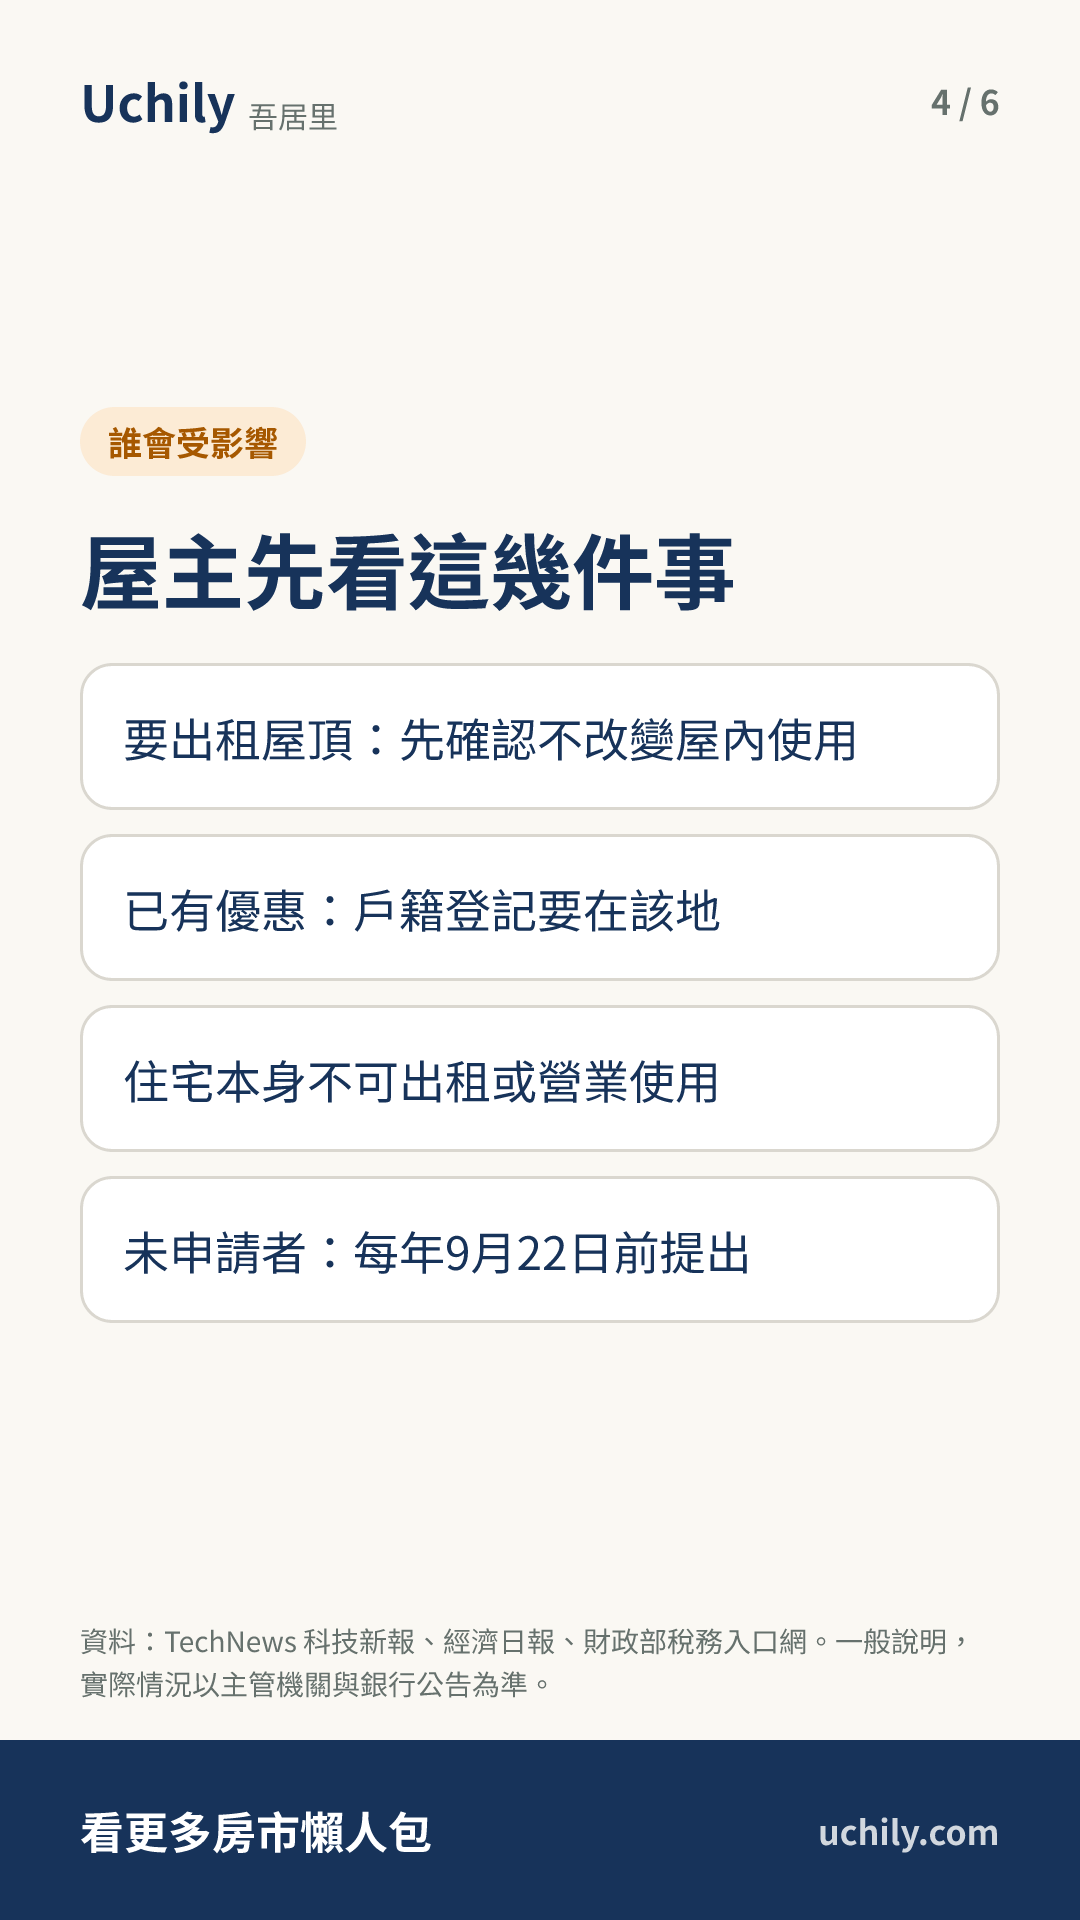
Homeowners who plan to lease their rooftops to solar power or base station companies should first confirm, before signing, that the leased content will not change the original interior use of the house. People who already enjoy the self-use residential rate should also keep in mind the household registration requirement and the condition that the residence is not leased or used for business. Those who have not yet applied for the preferential rate must submit their application by September 22 each year; after that, it takes effect starting with the period after the year of application.
Quick quiz
2 questions; pick an answer to see the explanation
- According to the Yunlin County Tax Bureau, what is the key point in determining whether the self-use residential rate still applies when a residential rooftop is leased for solar panels?
- What are the land value tax rate for self-use residential land and the basic rate for general land, respectively?
Image cards
6 cards. Tap to enlarge; save and share with friends
Original:財政部稅務入口網 · We only post summaries and key points. Read the original for the full story.
This week’s news, sorted for you
One Uchily newsletter a week, picking out what actually affects your wallet.
Subscribing creates a Uchily account with this email; open the link in the email to finish. You can unsubscribe from any email.