Bank Appraisal of NT$9 Million, Below the NT$10 Million Sale Price, Allows a Loan of Only NT$7.2 Million
When the appraisal is lower than the sale price, the loan amount is cut accordingly, and the buyer must cover the difference.

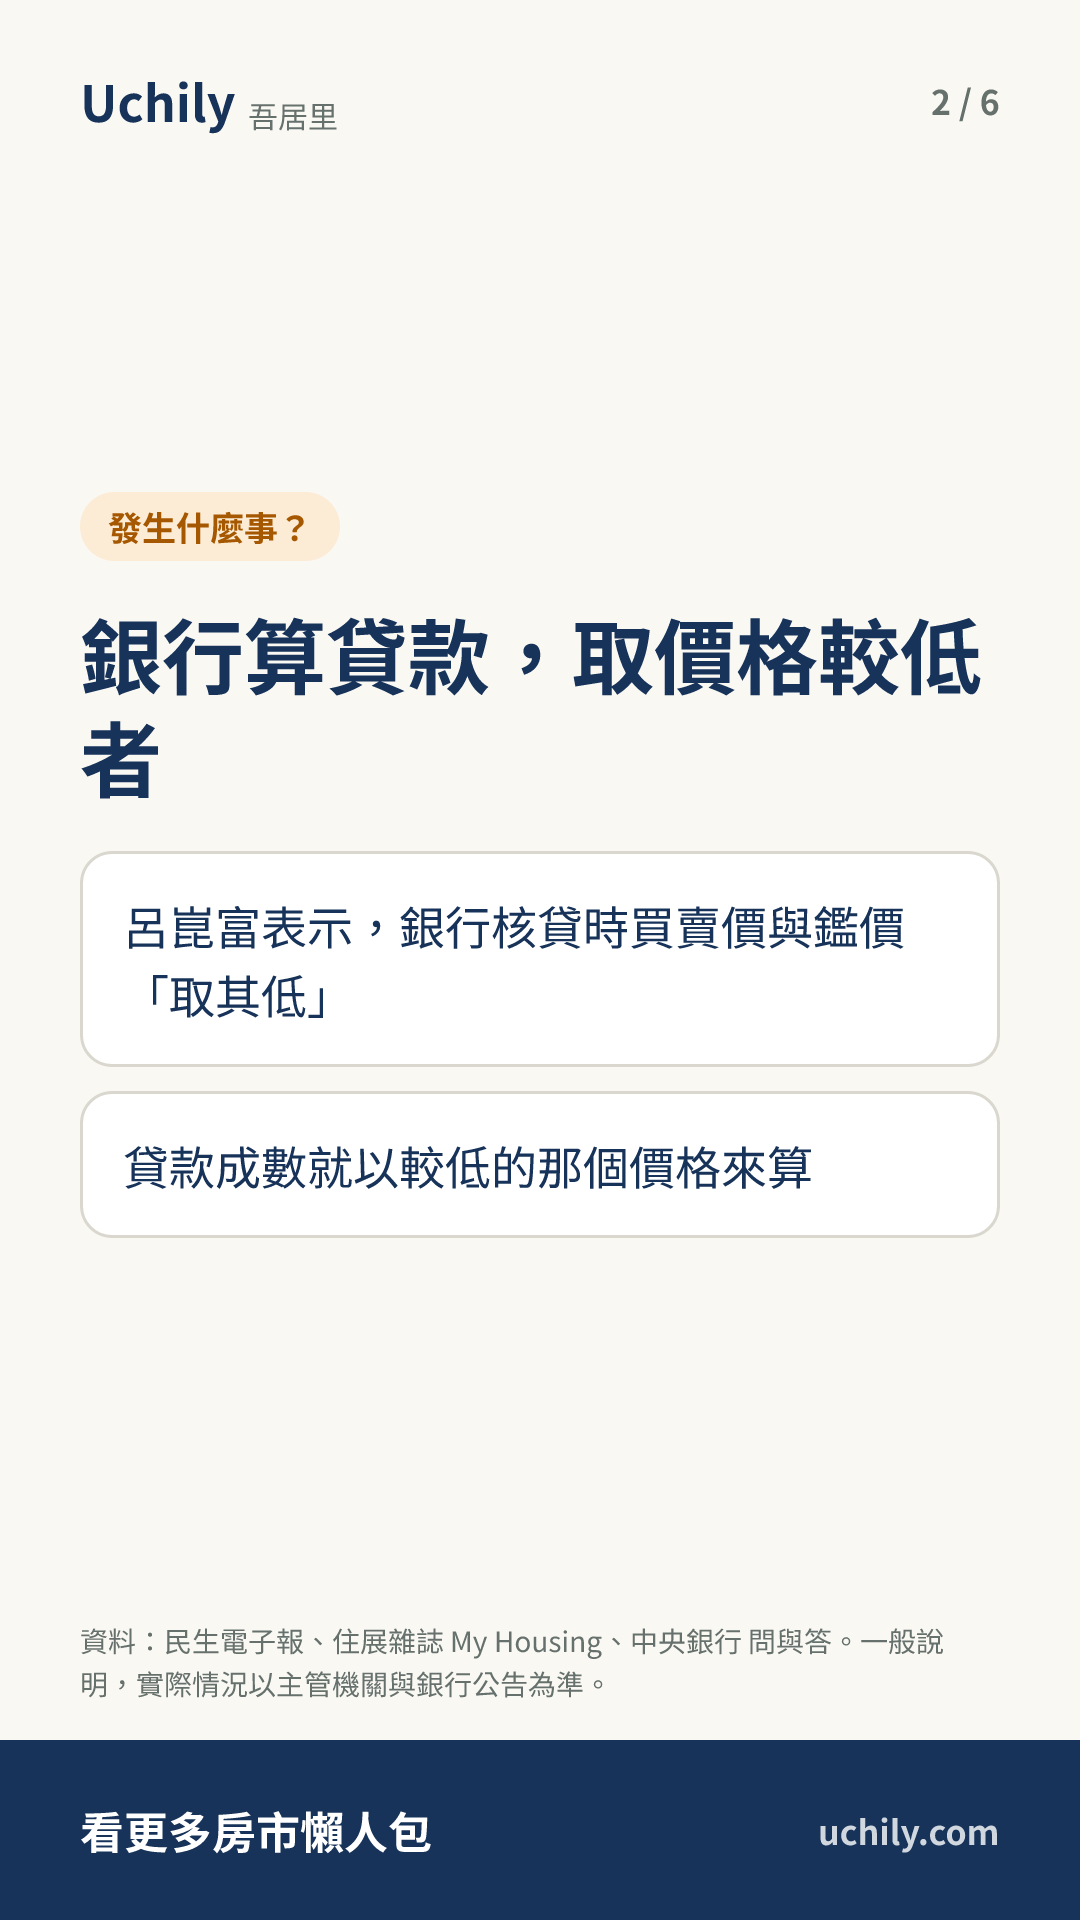
- Zhuzhan Magazine reports that banks calculate the loan based on the lower of the sale price and the appraised value, so when the appraisal is below the sale price, the buyer's down payment exceeds 20% of the sale price.
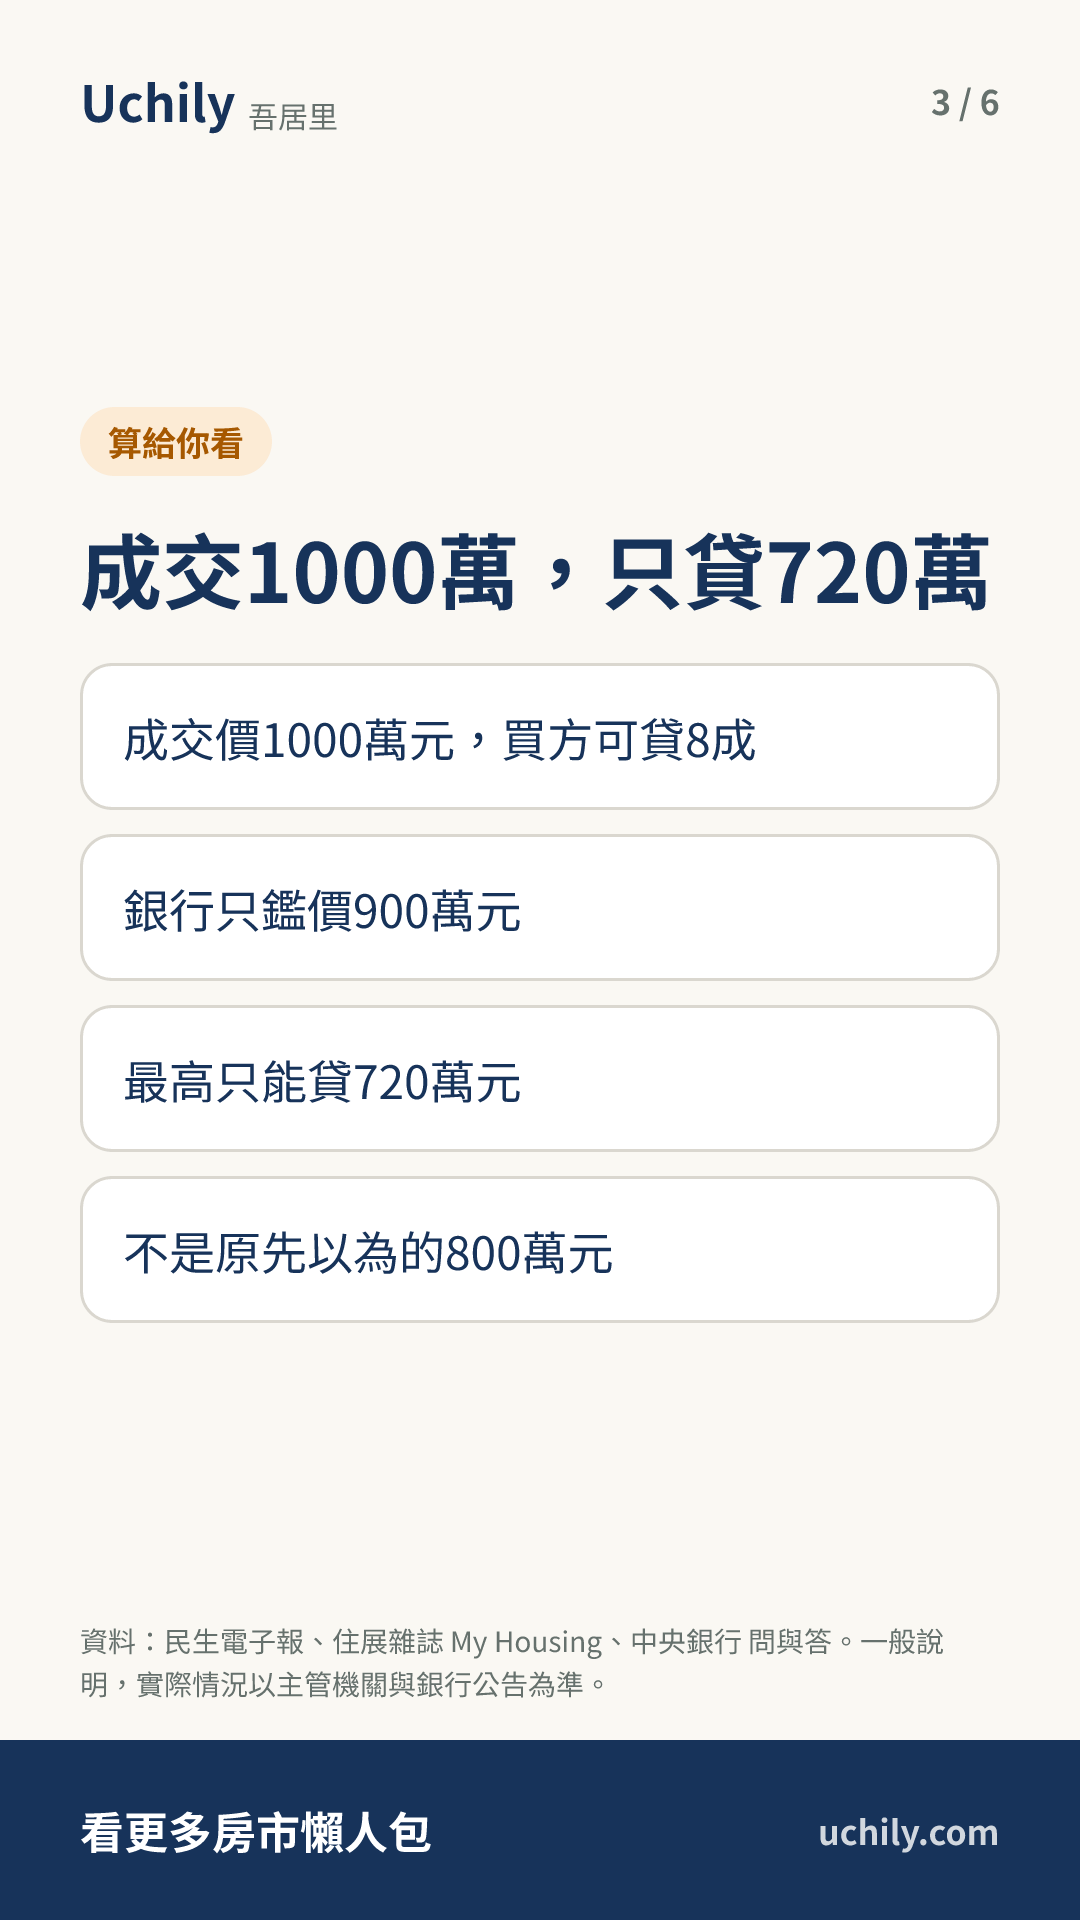
- For a home with a sale price of NT$10 million and a loan ratio of up to 80%, if the bank appraises it at NT$9 million, the maximum loan is only NT$7.2 million.
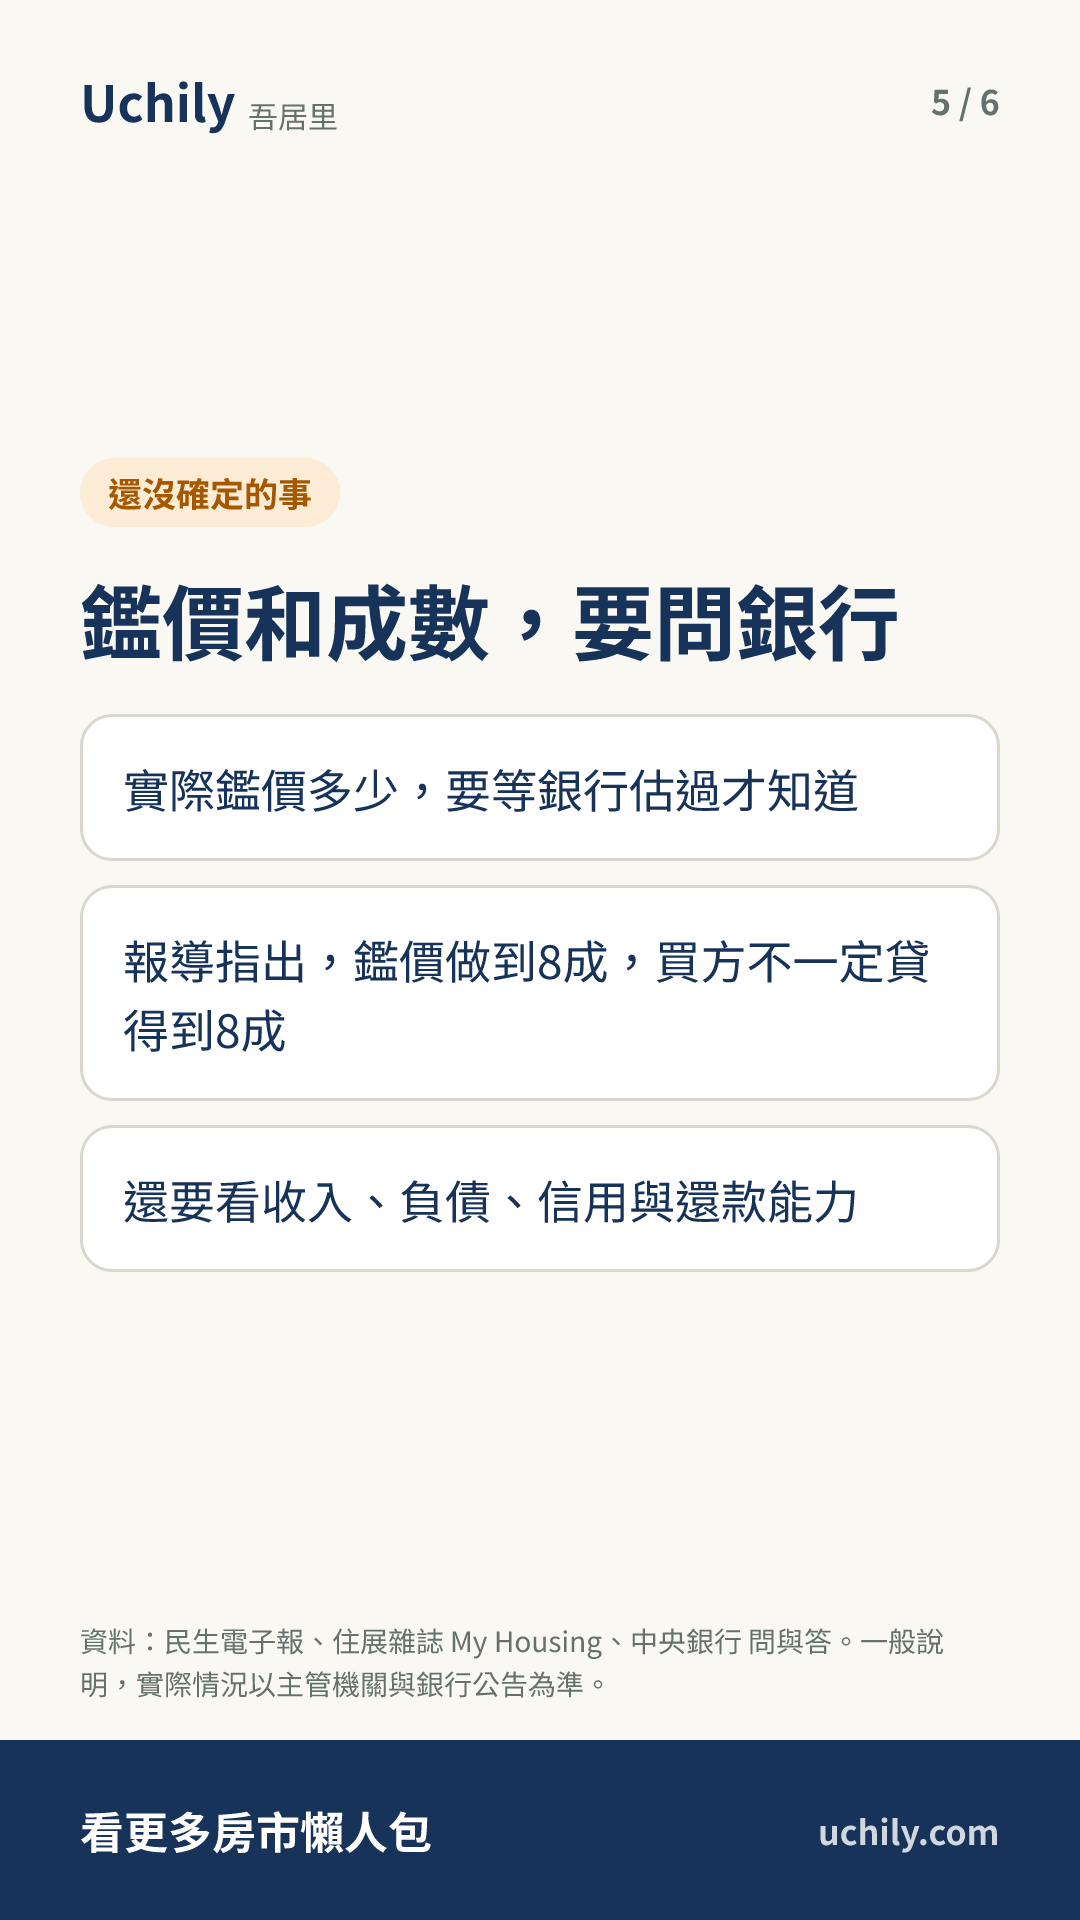
- An appraisal that supports an 80% loan does not mean the buyer will necessarily get 80%; income, debt, credit and repayment ability also matter.
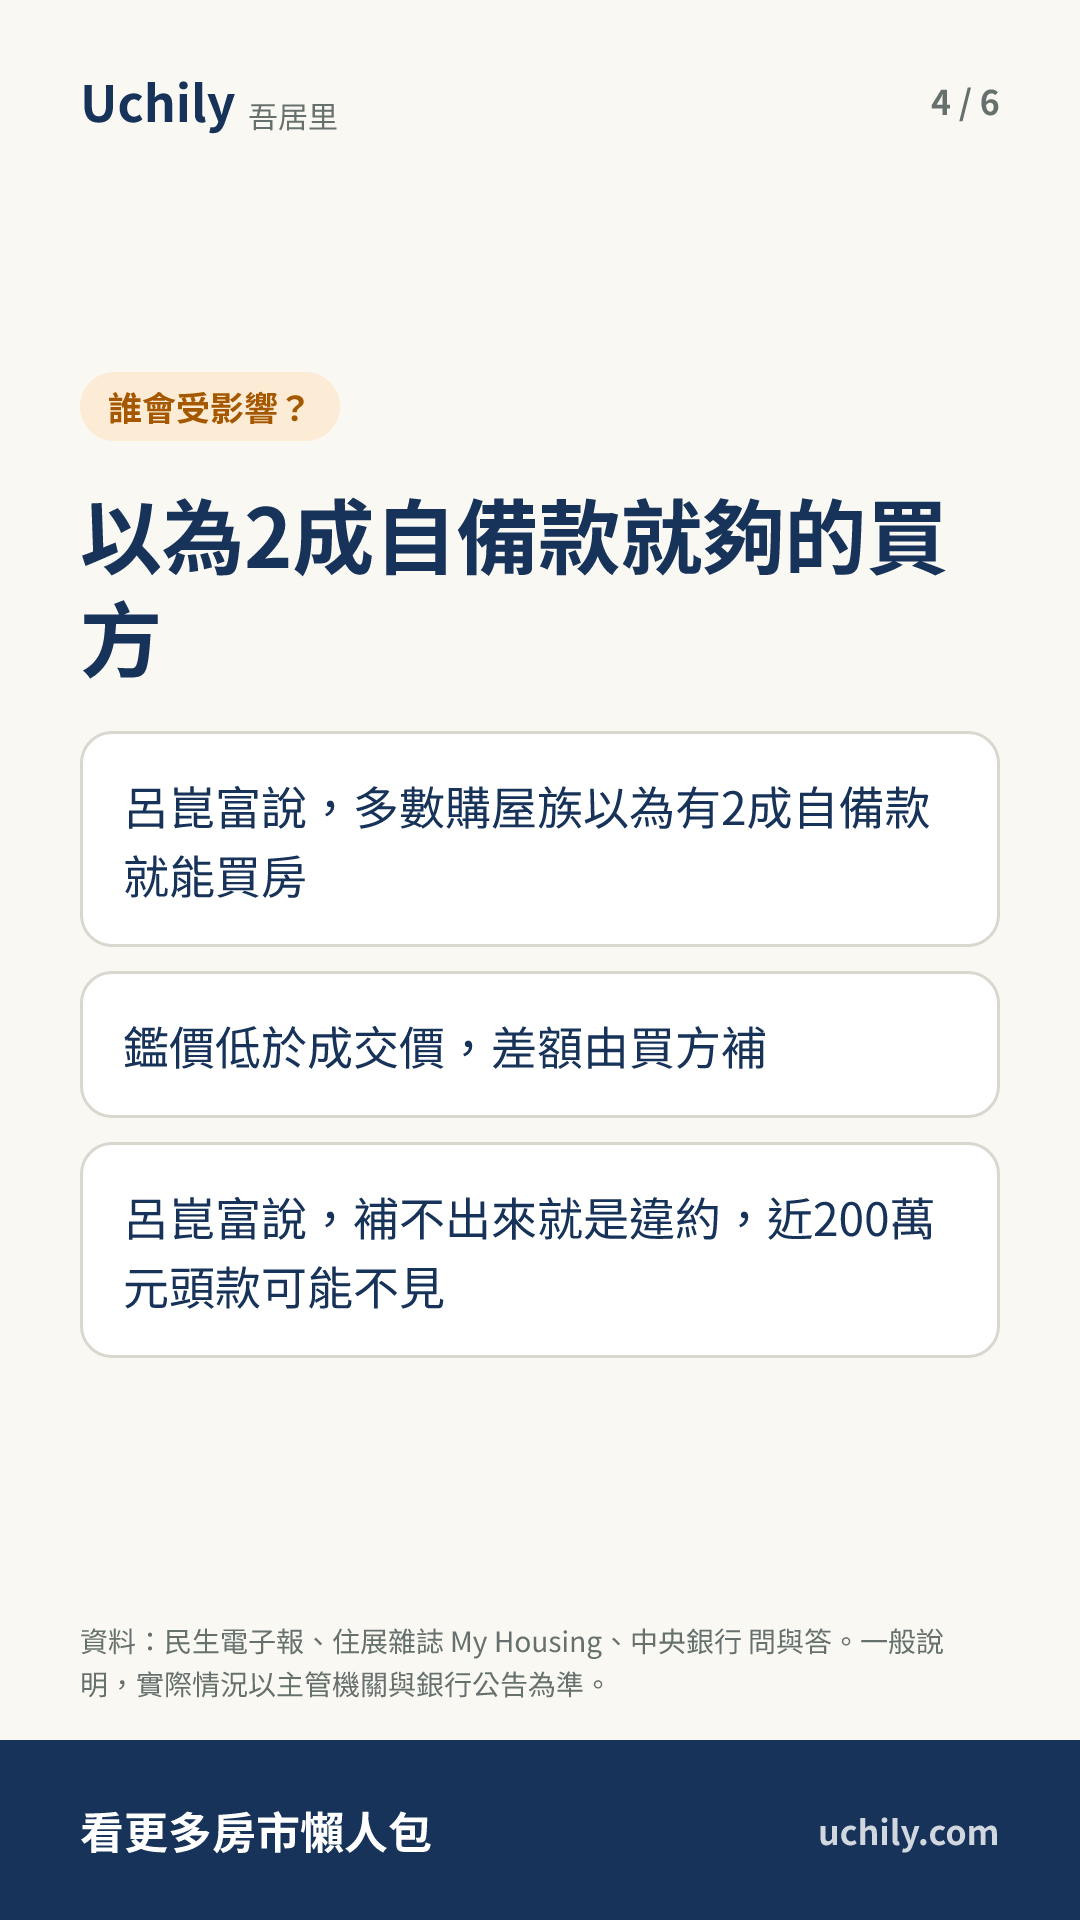
Lu Kun-fu, chairman of the Republic of China Real Estate Finance Knowledge Development Association, said that when banks approve loans, they "take the lower" of the sale price and the appraised value as the basis for calculating the loan ratio. He gave an example: for a home with a sale price of NT$10 million, even if the buyer can borrow 80%, if the bank appraises it at only NT$9 million, the maximum loan is NT$7.2 million, not the NT$8 million originally expected.
Lu Kun-fu said many homebuyers mistakenly believe that a 20% down payment is enough to buy a home. Once the bank's appraisal is lower than the sale price, the 80% loan they had expected is reduced, and the buyer makes up the difference. He also said: "If you can't come up with it, that is a breach of contract, and a down payment of nearly NT$2 million could be gone."
Another hypothetical case involves a sale price of NT$9 million, a maximum loan ratio of 80%, and a down payment of about NT$1.8 million. If the bank appraises the home at NT$8 million, the theoretical maximum loan is NT$6.4 million, and the buyer must prepare a down payment of at least NT$2.6 million; if the appraisal is NT$9 million, the theoretical maximum loan is NT$7.2 million.
Huang Chao-min, head of Zhengxin Real Estate Appraisers Joint Firm, noted that a home's sale price is the result of negotiation between a specific buyer and seller, and may be affected by the terms of the transaction and the buyer's preferences; a bank appraisal treats the home as collateral and assesses its market value. He said an appraisal is a lagging indicator of home prices: in a bull market the appraisal may be below market prices, and in a bear market it may be above them.
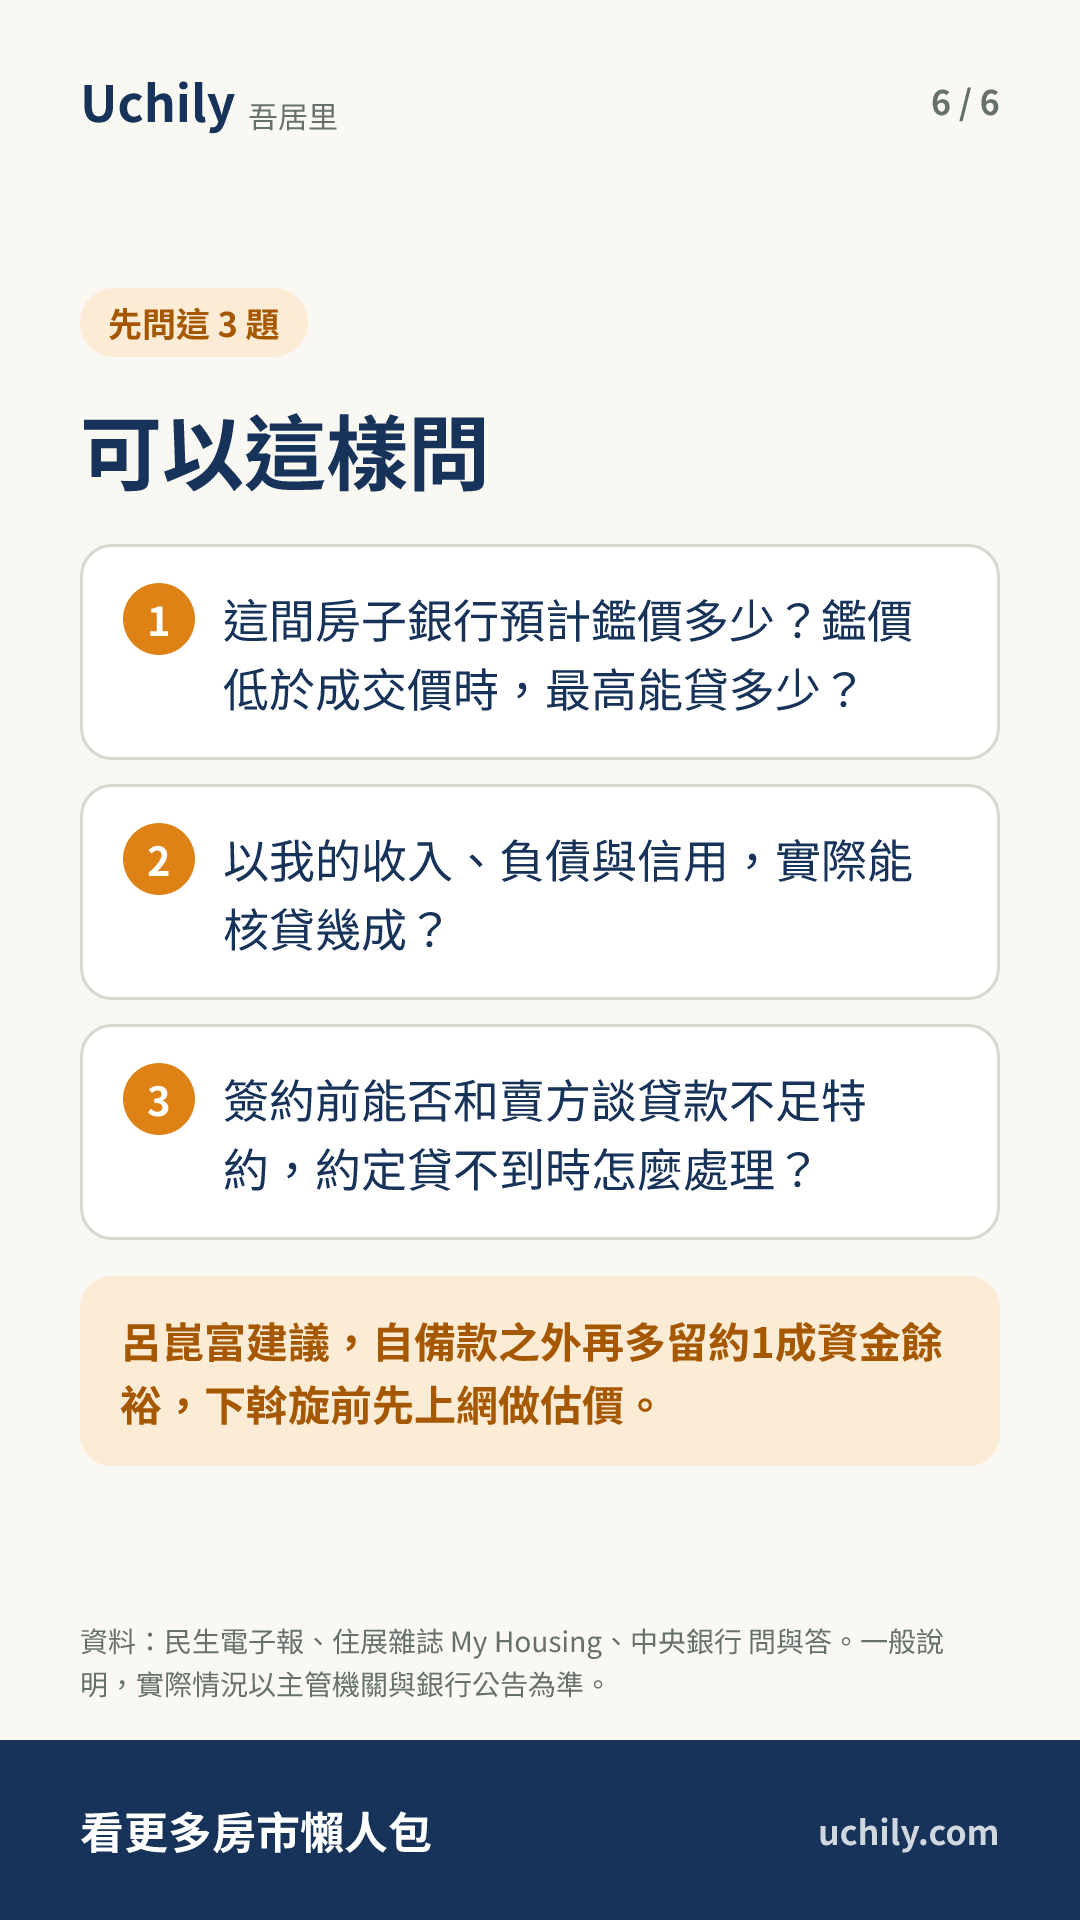
In Zhouziyang, Wugu, New Taipei, one buyer got only a 70% loan because the appraisal fell short, had to raise nearly NT$1 million more in down payment at short notice, and in the end borrowed from a financing company to complete the handover. Lu Kun-fu advises that, in addition to the down payment originally prepared, buyers keep about 10% more in funds as a cushion, and get an online valuation before making an offer; submitting formal applications to 3 banks is about right, and a special clause for loan shortfall can be negotiated with the seller before signing the contract, specifying the minimum loan amount or ratio to be obtained and how matters will be handled if the loan cannot be obtained.
People preparing to buy a home should not count on a down payment of just 20% of the sale price when calculating their funds; they should also factor in the possible gap if the appraisal comes in below the sale price. They can follow Lu Kun-fu's advice to keep about 10% more in funds as a cushion and get an online valuation before making an offer. Before signing the contract, they can also negotiate a special clause for loan shortfall with the seller, agreeing in advance on how to handle the situation if the loan cannot be obtained.
Loan-to-value calculator
- Loan amount
- 1,400 × NT$10K
- Down payment
- 600 × NT$10K
- Monthly payment
- NT$54,023
- Total interest
- 545 × NT$10K
The default rate of 2.321% is the central bank’s published August average rate on new mortgages at the five major banks. Equal monthly payments, no grace period; the bank’s approval is final.
Quick quiz
2 questions; pick an answer to see the explanation
- A home has a sale price of NT$10 million and the buyer can borrow 80%, but the bank appraises it at only NT$9 million. What is the maximum loan?
- In addition to the down payment originally prepared, how much more in funds does Lu Kun-fu recommend buyers keep as a cushion?
Image cards
6 cards. Tap to enlarge; save and share with friends
Original:中央銀行 問與答 · We only post summaries and key points. Read the original for the full story.
This week’s news, sorted for you
One Uchily newsletter a week, picking out what actually affects your wallet.
Subscribing creates a Uchily account with this email; open the link in the email to finish. You can unsubscribe from any email.