Personal Loan Balance Hits Record NT$22.9 Trillion; Working Capital Up Over NT$1 Trillion This Year
Personal loans at all banks reached a new all-time high. Of this year's increase, working capital accounts for most, while real estate purchases posted the smallest growth.

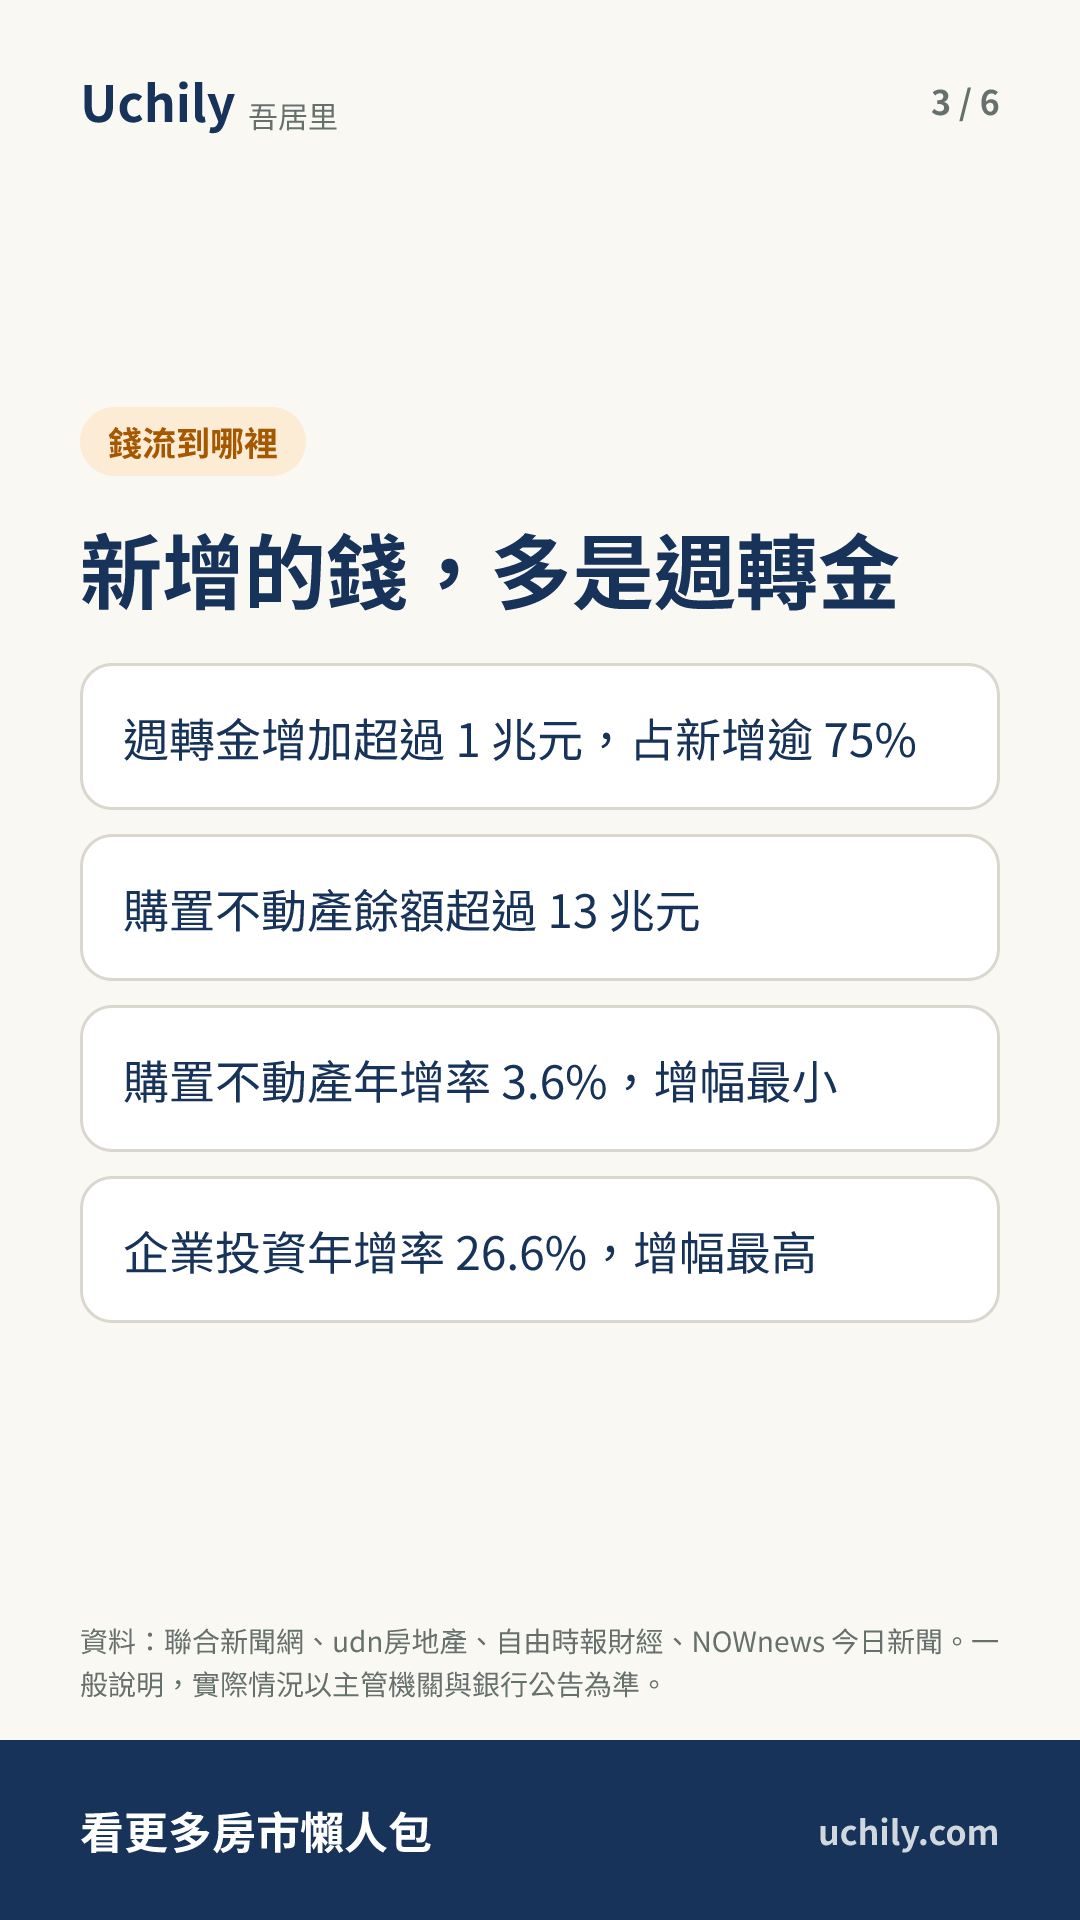
- Central Bank data compiled by Taiwan Realty Group show that personal loans rose by about NT$1.4 trillion this year, of which working capital increased by more than NT$1 trillion.
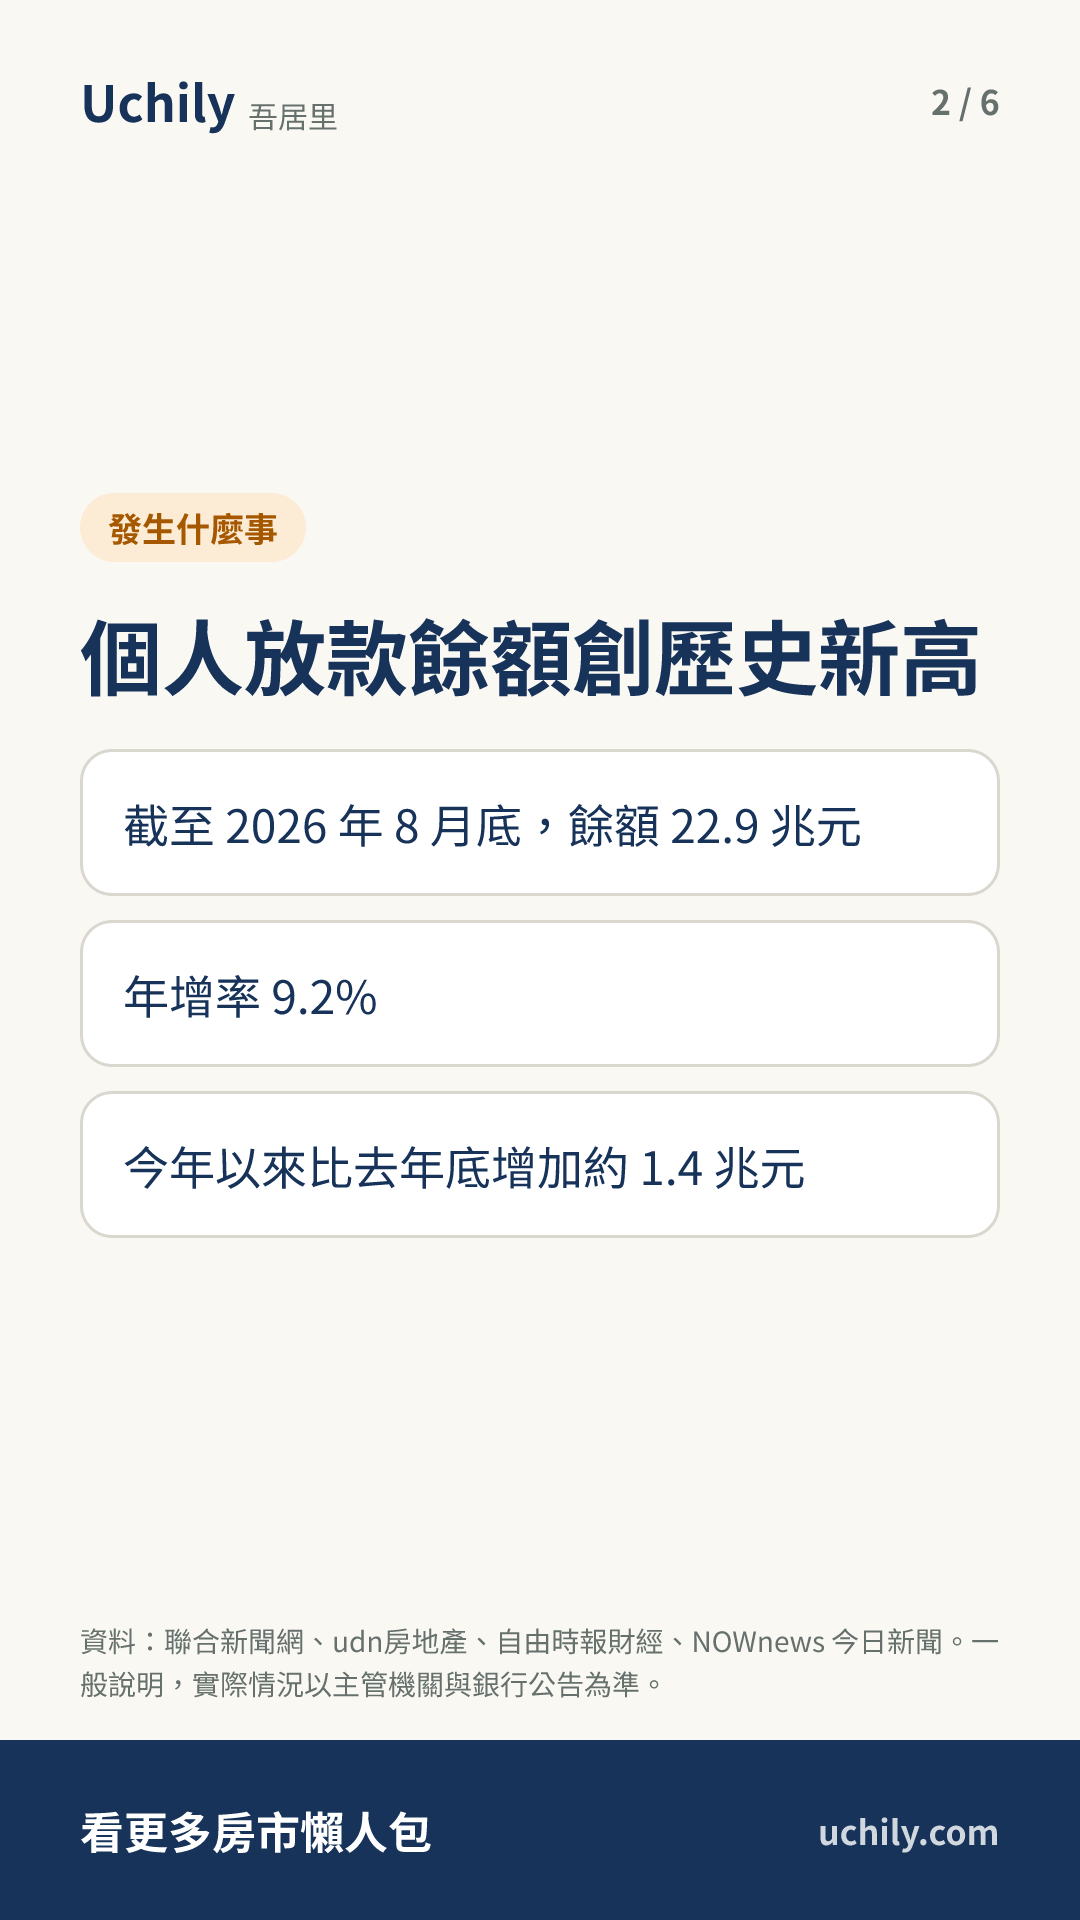
- As of the end of August 2026, the personal loan balance at all banks stood at NT$22.9 trillion, a record high, up 9.2% year on year.
- The balance of loans for real estate purchases exceeded NT$13 trillion, but its year-on-year growth was only 3.6%, the smallest among all loan purposes.
According to Central Bank data (compiled by Taiwan Realty), as of the end of August 2026, the personal loan balance at all banks was NT$22.9 trillion, another record high, up 9.2% year on year.
The personal loan balances for all four main purposes, namely real estate purchases, movable property purchases, business investment and working capital, climbed to record highs. Business investment saw the highest growth, at 26.6% year on year.
The personal loan balance has increased by about NT$1.4 trillion since the end of last year. Working capital rose by more than NT$1 trillion, accounting for over 75% of the increase, making it the biggest driver. The balance for real estate purchases is the highest, but its year-on-year growth of 3.6% is the lowest among all purposes.
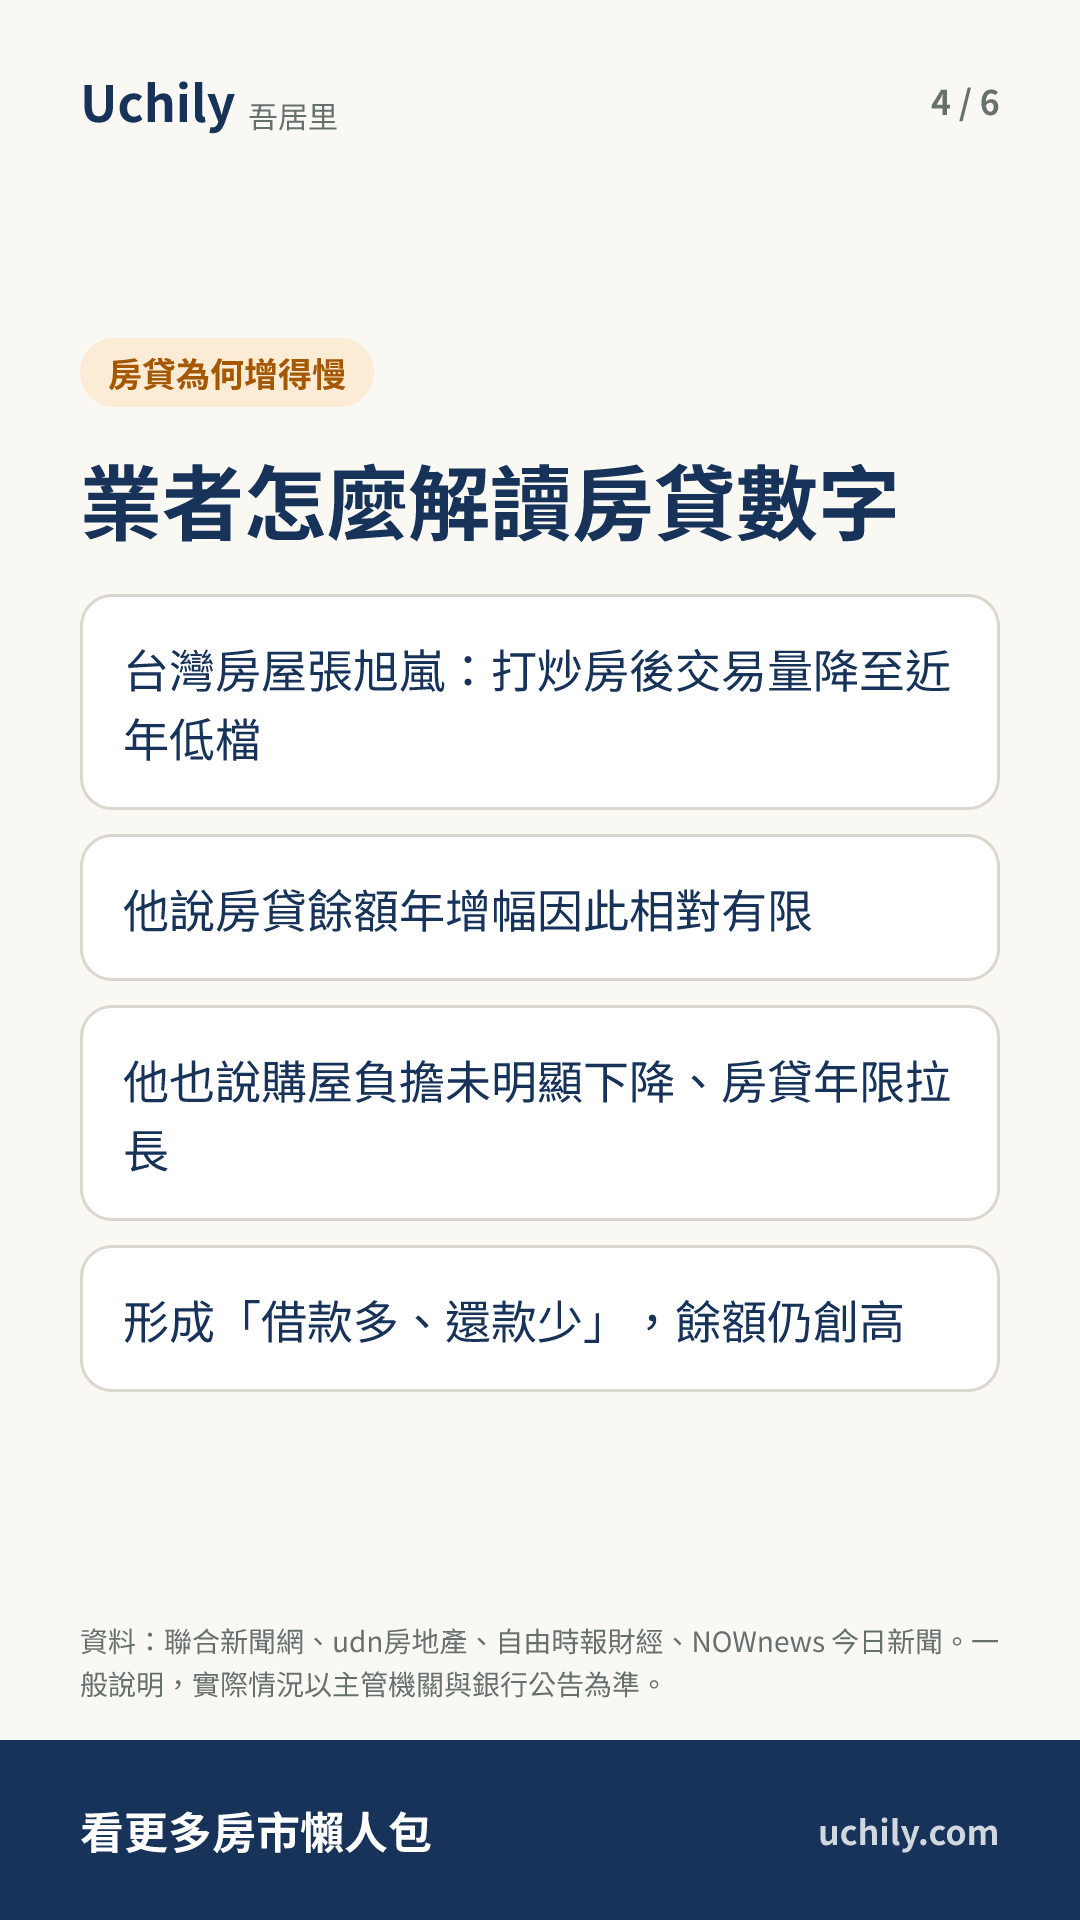
Chang Hsu-lan, CEO of the Trend Center at Taiwan Realty Group, said that the government has continued to crack down on property speculation in recent years, and housing transaction volume has fallen to a low in recent years, so year-on-year growth in the mortgage balance has been relatively limited.
Chang Hsu-lan also said that the burden of buying a home has not fallen noticeably, and mortgage terms keep getting longer, creating a situation of "borrowing a lot, repaying little," so the balance of loans for real estate purchases still hit another record.
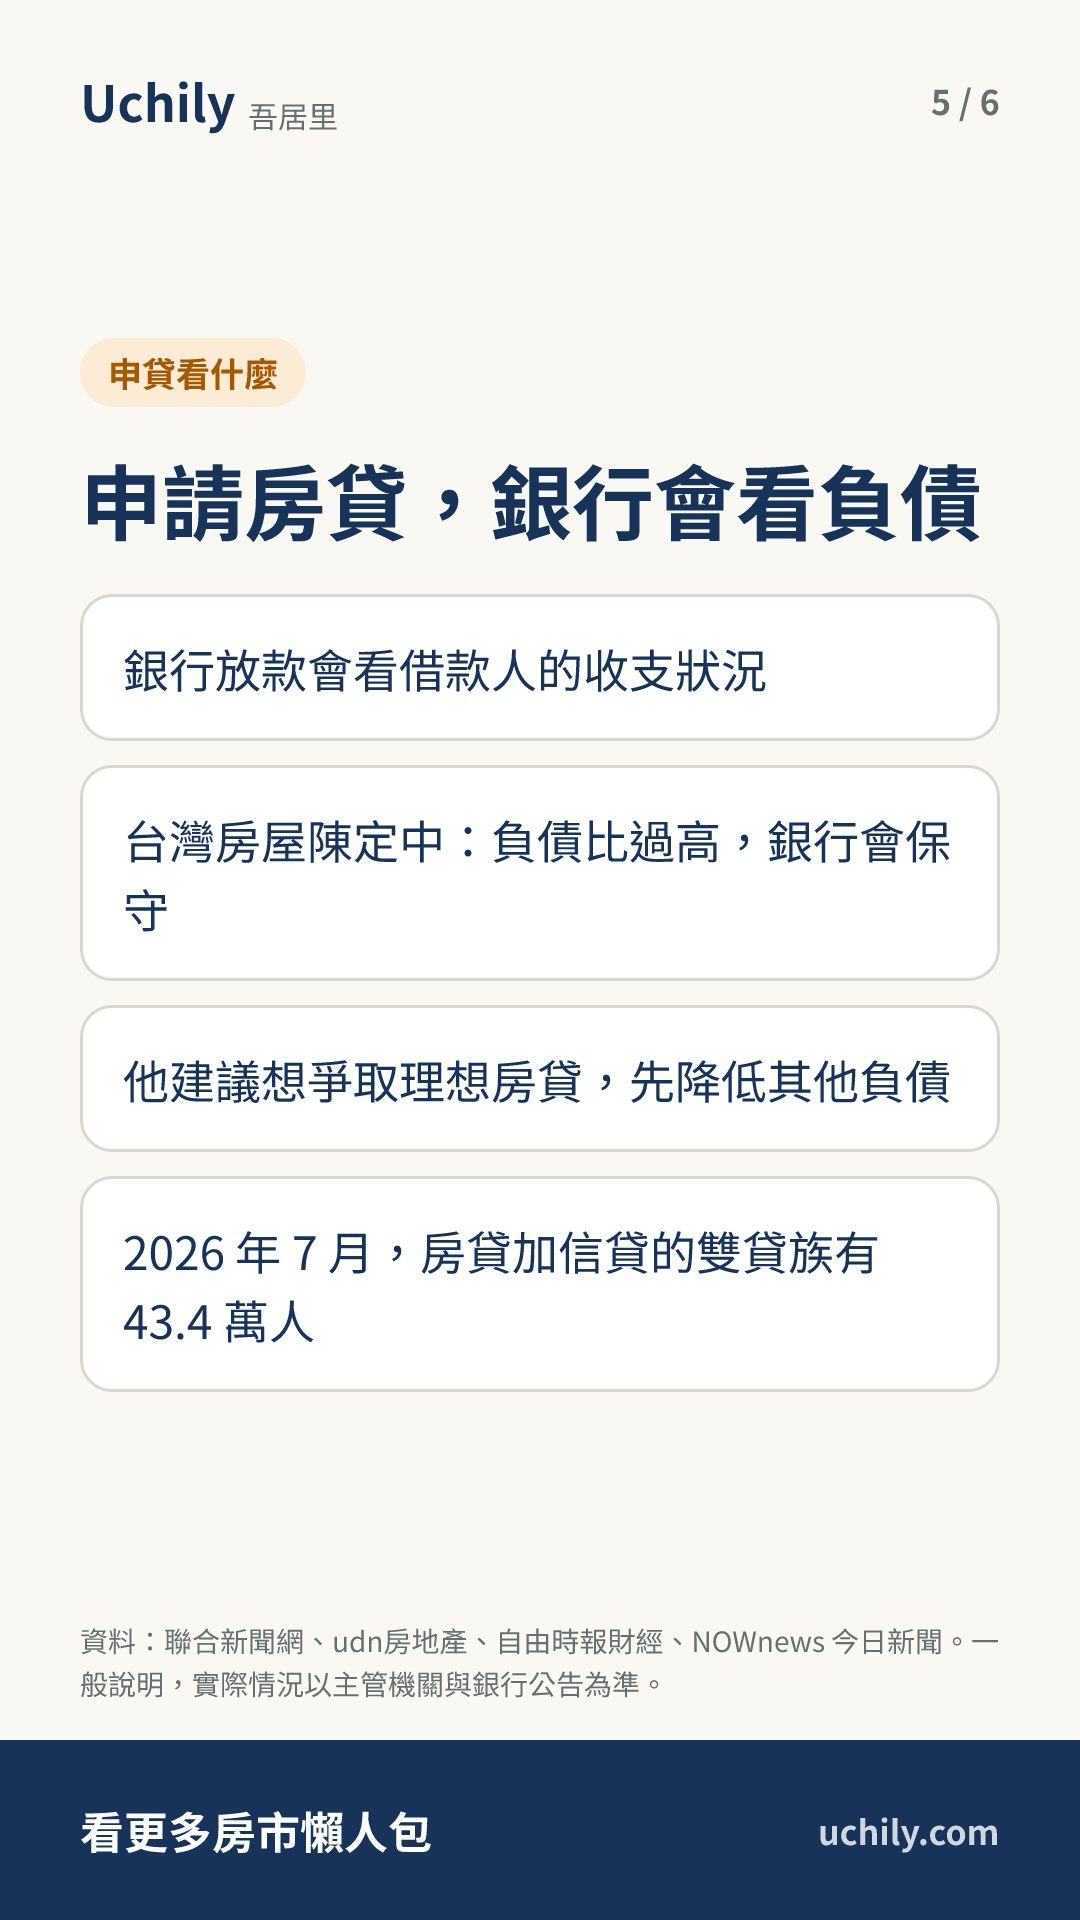
Chen Ting-chung, senior manager at the Trend Center of Taiwan Realty Group, noted that banks consider a borrower's income and expenses when lending; when a borrower's debt ratio is too high, banks will be conservative.
For people applying for a mortgage or a loan to trade up to another home, banks will look at their income and expenses and debt ratio. Chen Ting-chung, senior manager at the Trend Center of Taiwan Realty Group, suggested that people who want to secure a desirable mortgage first reduce their debt from other sources. Those who already have a mortgage can also review their other loans.
Quick quiz
2 questions; pick an answer to see the explanation
- Of the roughly NT$1.4 trillion in new personal loans so far this year, which purpose increased the most?
- Among the personal loan purposes, which had the highest year-on-year growth?
Image cards
6 cards. Tap to enlarge; save and share with friends
Original:聯合新聞網 · We only post summaries and key points. Read the original for the full story.
This week’s news, sorted for you
One Uchily newsletter a week, picking out what actually affects your wallet.
Subscribing creates a Uchily account with this email; open the link in the email to finish. You can unsubscribe from any email.