Mortgage NPLs reach NT$9,759 million at end-September 2026, a 5.5-year high
Domestic banks' mortgage non-performing loans have climbed to their highest level since March 2021, and non-performing construction loans are at a 17-month high.

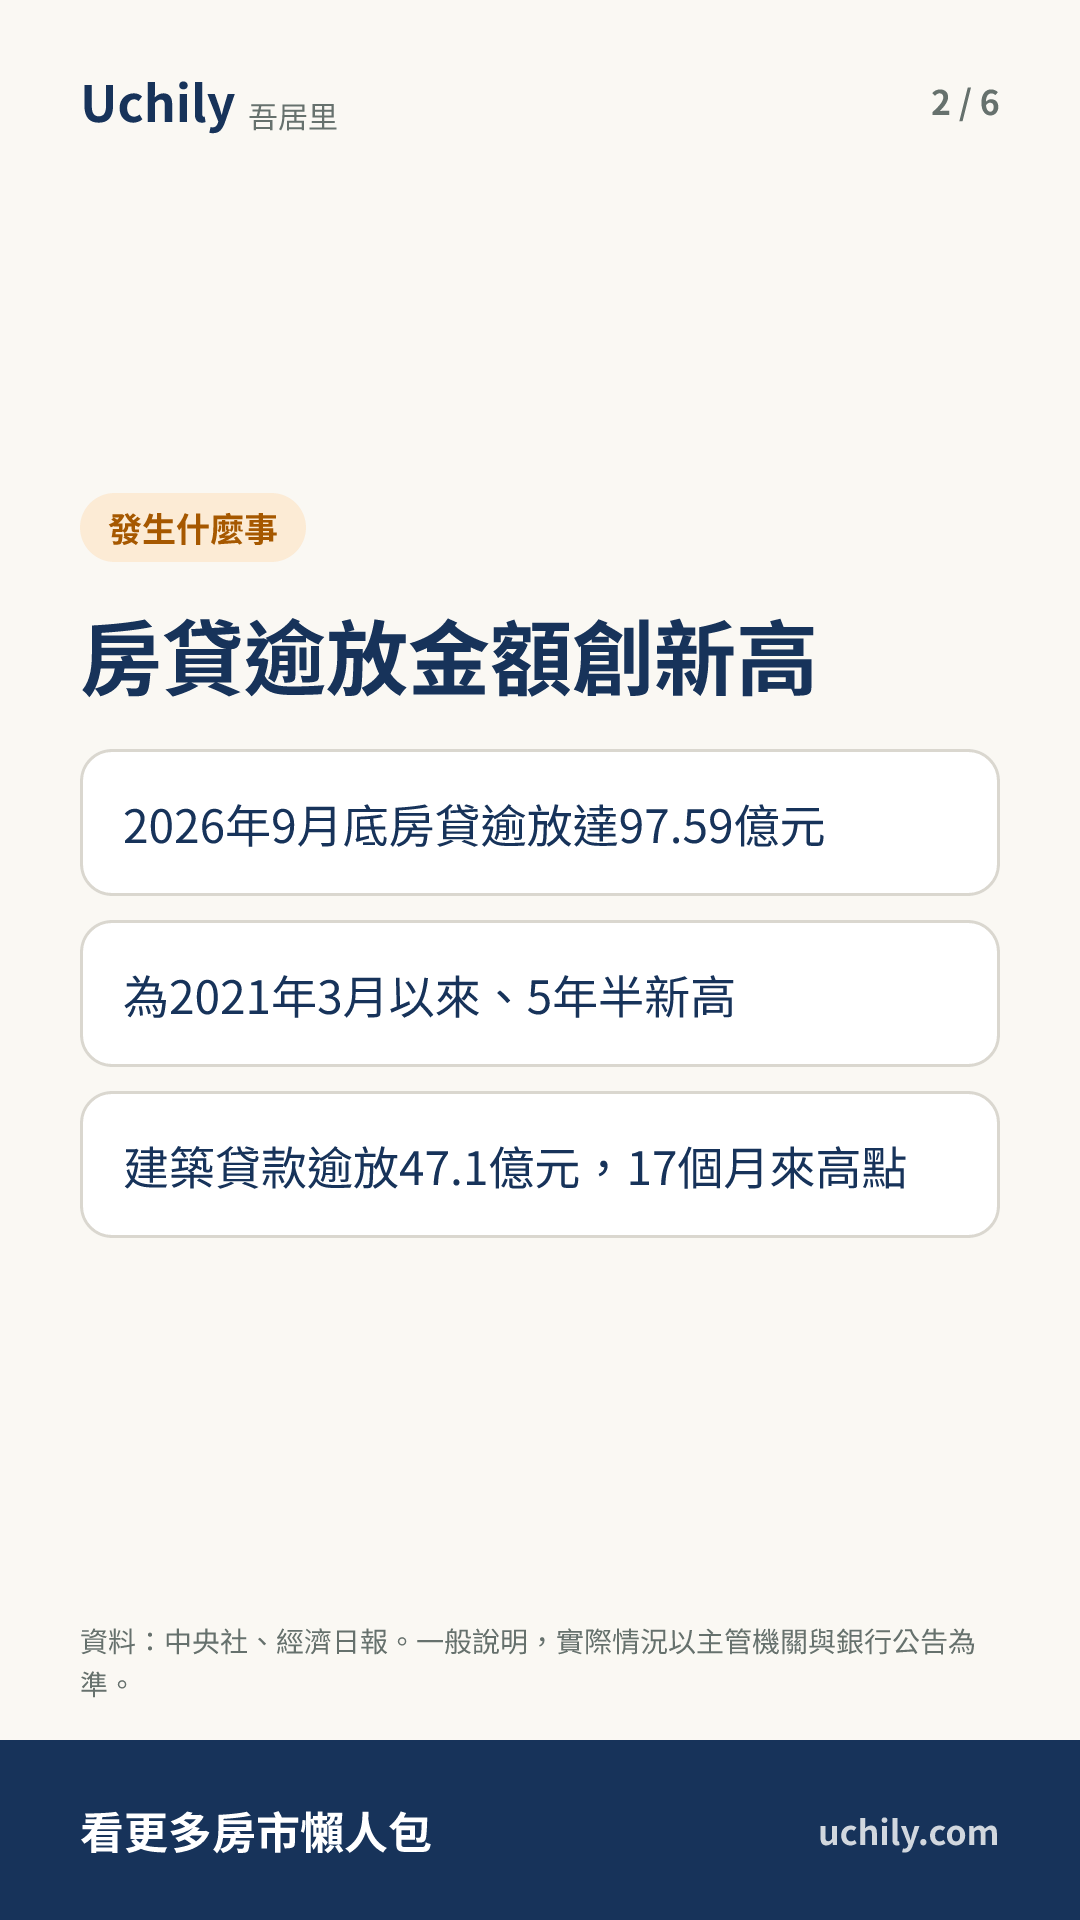
- According to Financial Supervisory Commission (FSC) statistics, domestic banks' mortgage non-performing loans stood at NT$9,759 million at the end of September 2026, a 5.5-year high.
- At the end of September 2026, domestic banks' non-performing construction loans were NT$4,710 million, a 17-month high.
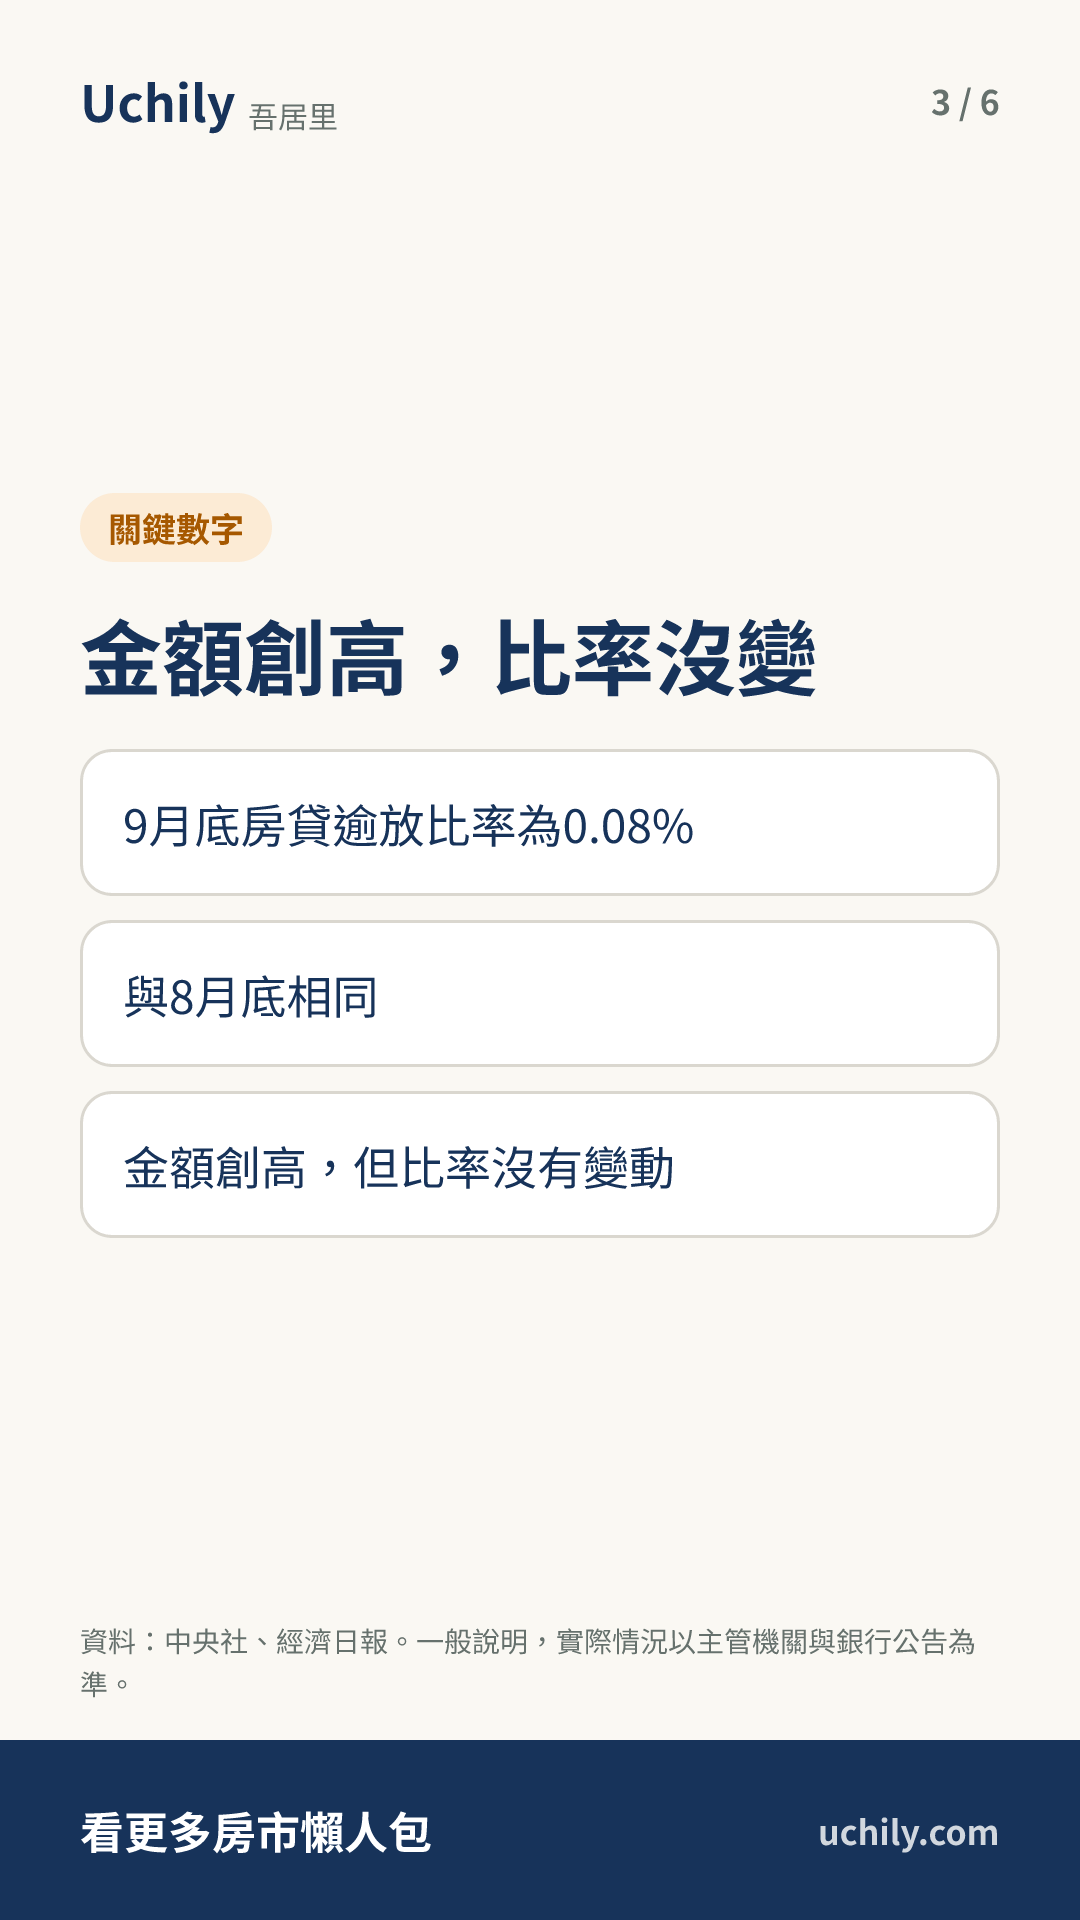
- At the end of September 2026, the mortgage NPL ratio at domestic banks was 0.08%, the same as at the end of August.
Non-performing loans (NPLs) are overdue loans, meaning loans on which the borrower has not repaid on time as agreed. Domestic banks' mortgage NPLs reached NT$9,759 million at the end of September 2026. The last time the level was this high was March 2021, about 5.5 years earlier.
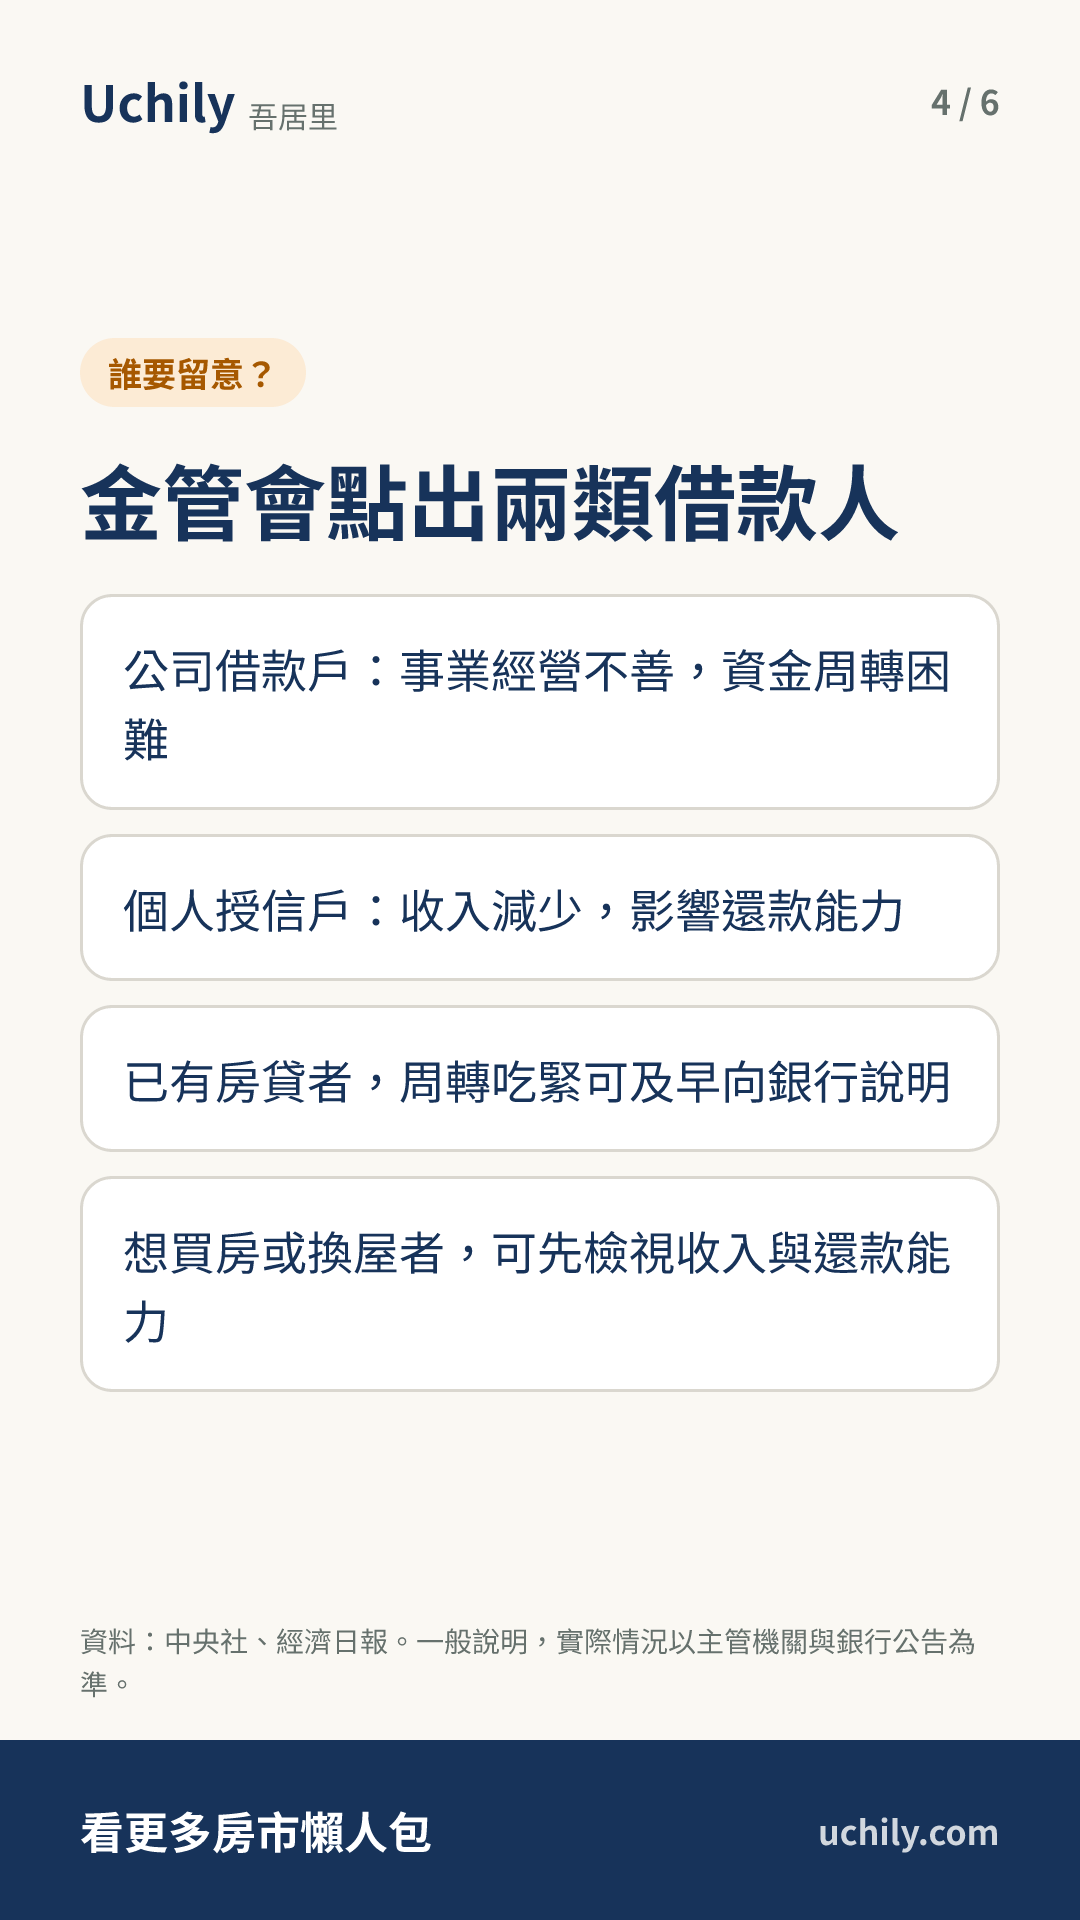
The FSC said there are two backgrounds to the rise in NPLs: first, company borrowers are doing poorly in business and facing tight cash management; second, individual borrowers have seen their income fall, which has affected their ability to repay.
Construction loans show a similar trend. At the end of September 2026, non-performing construction loans were NT$4,710 million, a 17-month high.
Although the amount has risen, the ratio has not changed: at the end of September 2026, the mortgage NPL ratio at domestic banks was 0.08%, the same as at the end of August.
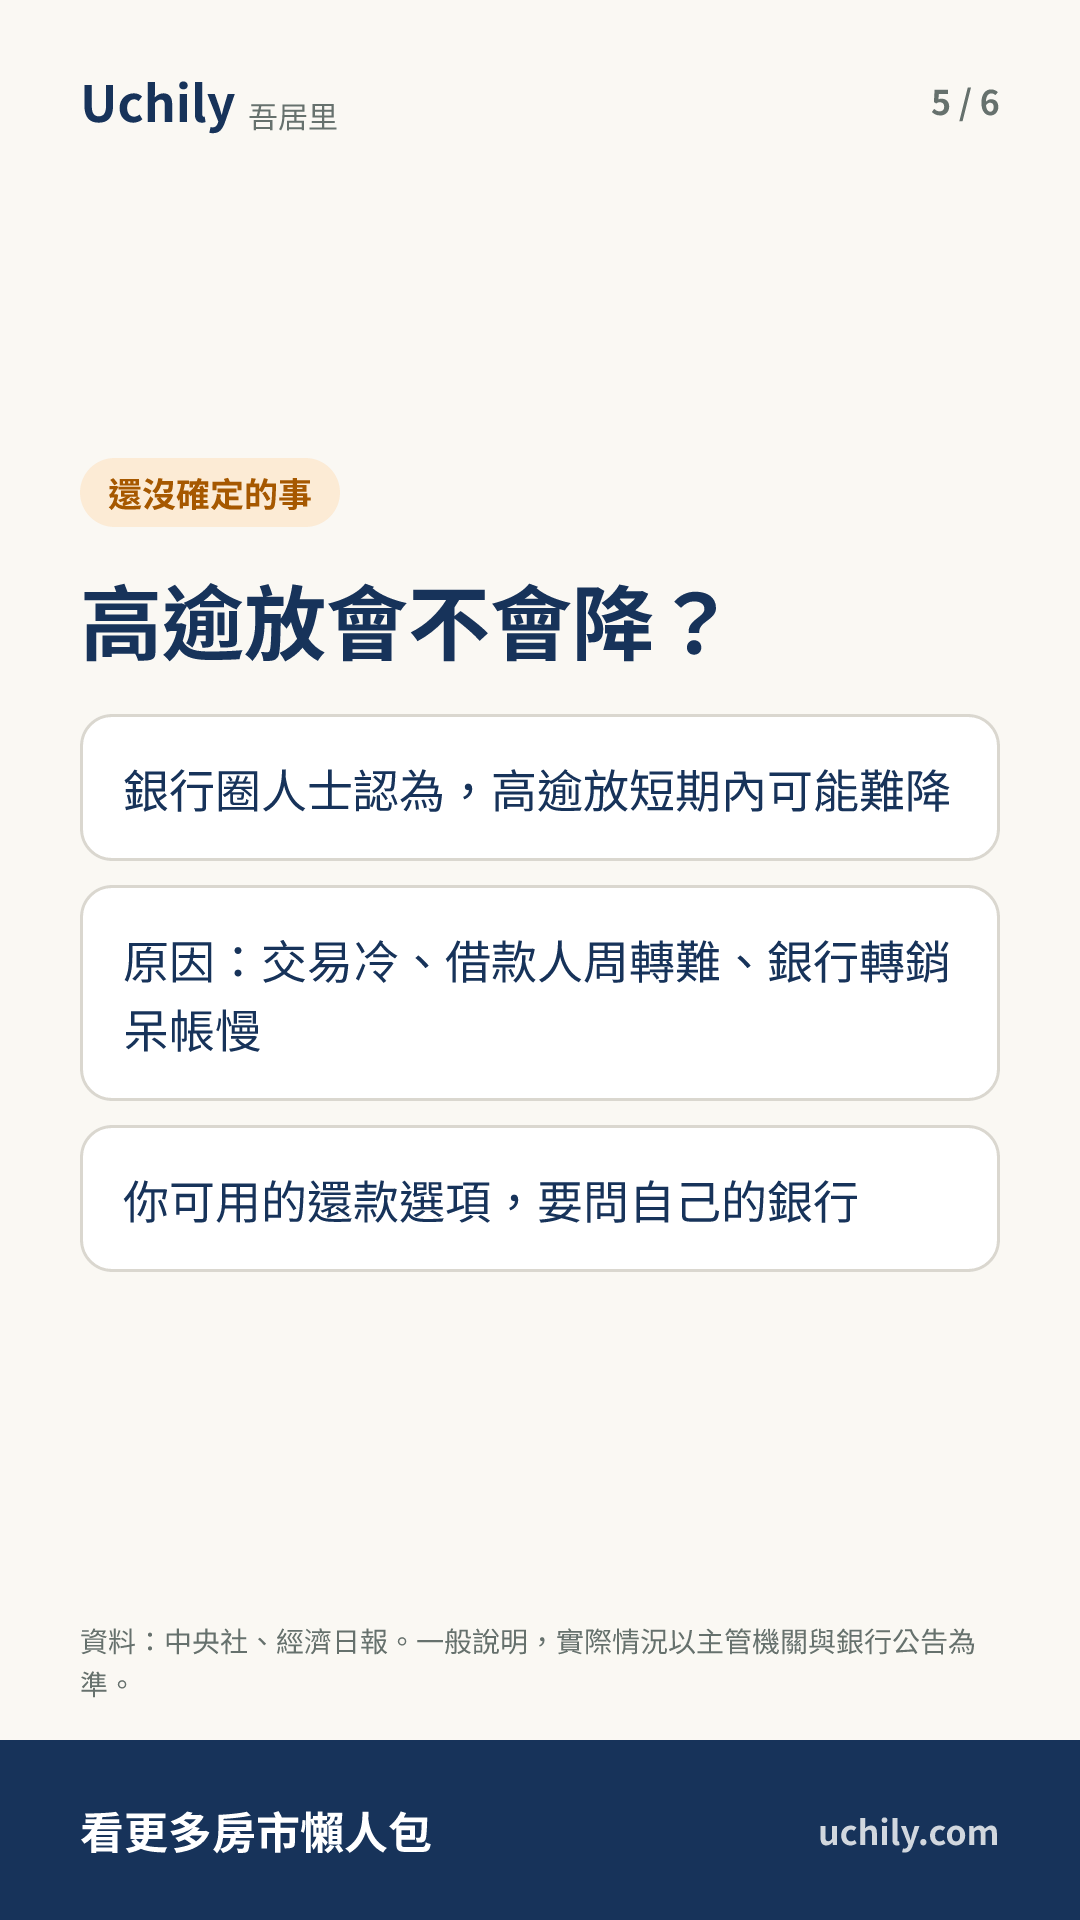
People in the banking industry believe that, with property transactions sluggish, borrowers finding it hard to manage cash flow, and banks slow to write off bad debts, high NPLs may not easily come down in the short term.
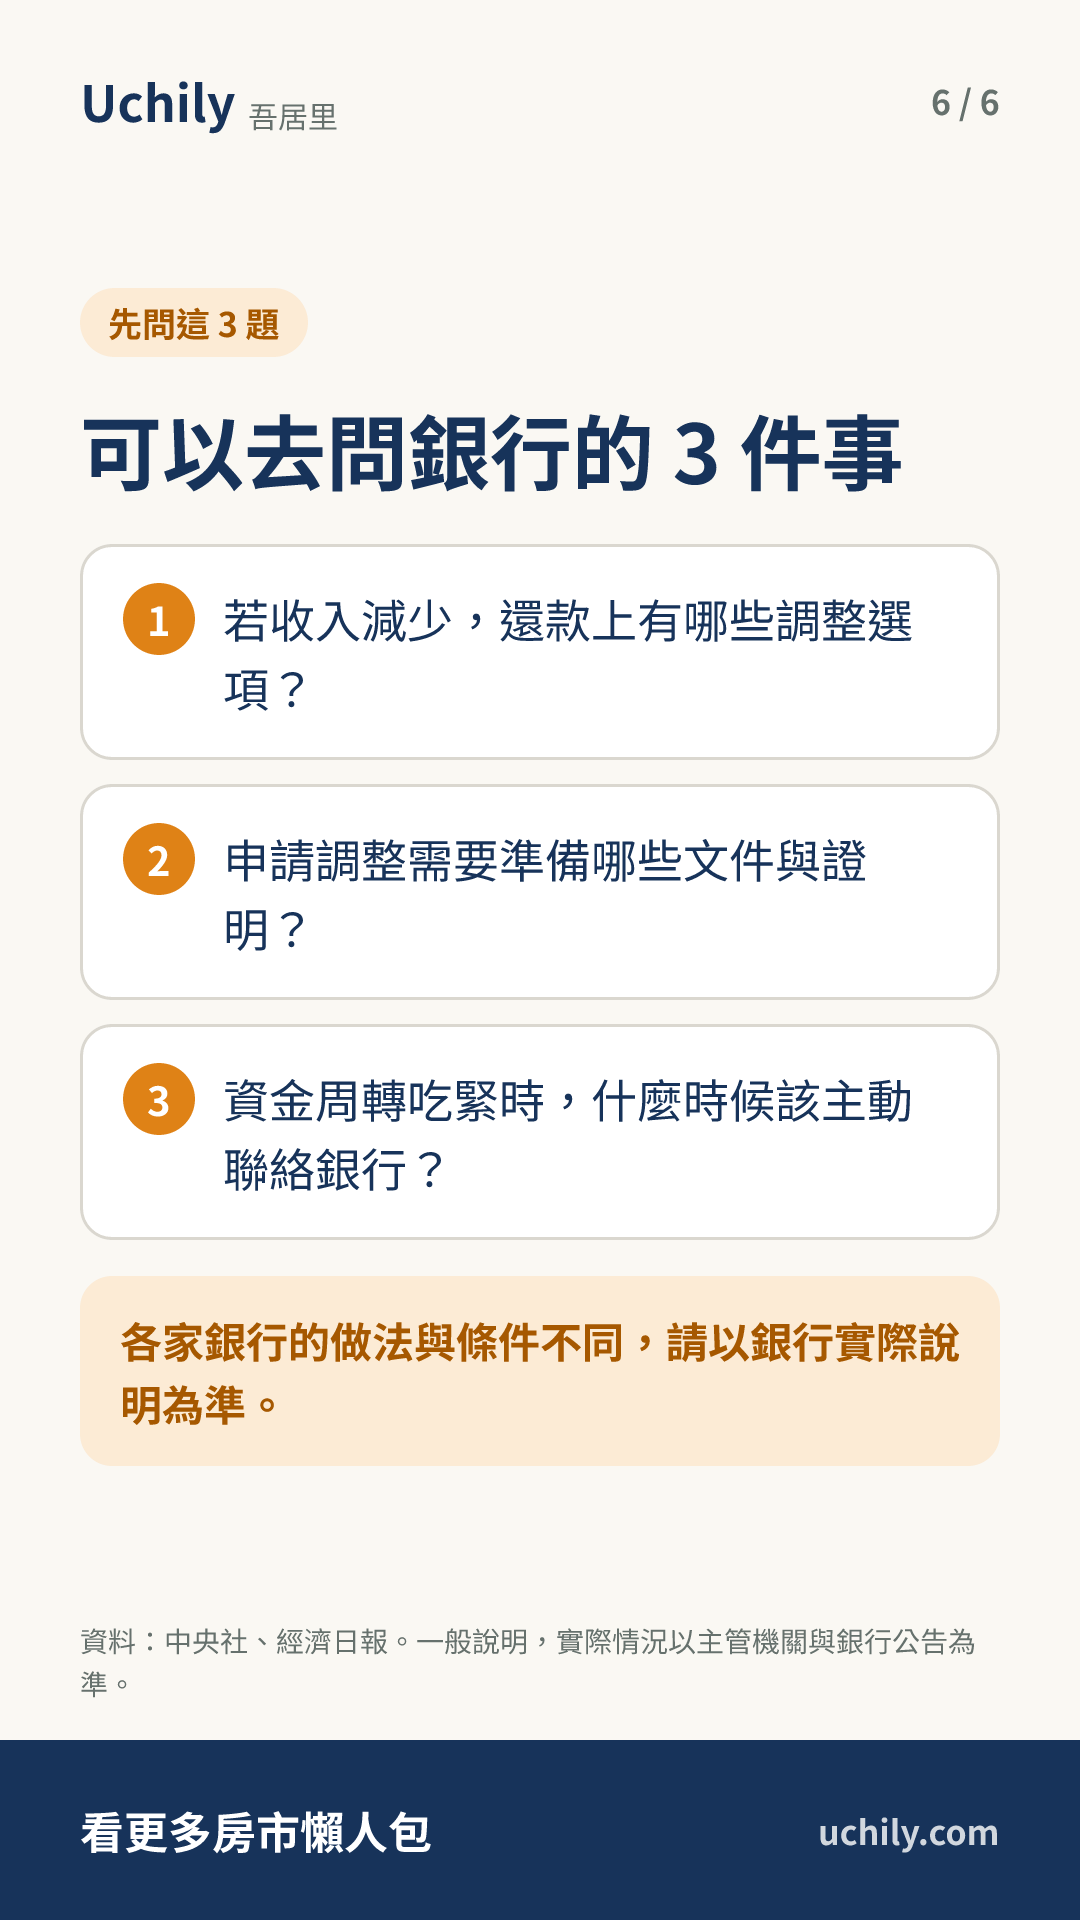
Homeowners with a mortgage whose income has fallen or whose cash flow is tight can explain their situation to the bank early and learn about their repayment options. People who want to buy or trade up can first review their income and repayment ability. The NPL ratio of 0.08% is the same as at the end of August; the amount is at a record high, but the ratio has not changed.
Quick quiz
2 questions; pick an answer to see the explanation
- What was the amount of domestic banks' mortgage NPLs at the end of September 2026?
- According to the FSC, what is the reason mortgage NPLs have increased?
Image cards
6 cards. Tap to enlarge; save and share with friends
Original:中央社 · We only post summaries and key points. Read the original for the full story.
This week’s news, sorted for you
One Uchily newsletter a week, picking out what actually affects your wallet.
Subscribing creates a Uchily account with this email; open the link in the email to finish. You can unsubscribe from any email.